
Business Solutions
Long-Conical Peppers: How Heat-Tolerant Sweet Varieties Are Changing the Long Red Pepper

| Key Takeaways
• Long-conical peppers are slender, tapered sweet peppers (Capsicum annuum) usually sold fully red and positioned as a premium culinary format. • Very little pepper fruit set occurs above 90°F during the day or below 60°F at night, and fruit that sets above 85°F is often small and misshapen. • Parthenocarpy, fruit development without fertilization, helps some pepper lines keep setting fruit when heat reduces pollen viability. • Retail long red peppers are typically harvested at about 90% red color before noon and precooled to 10 to 12°C immediately after picking. |
What are long-conical peppers?
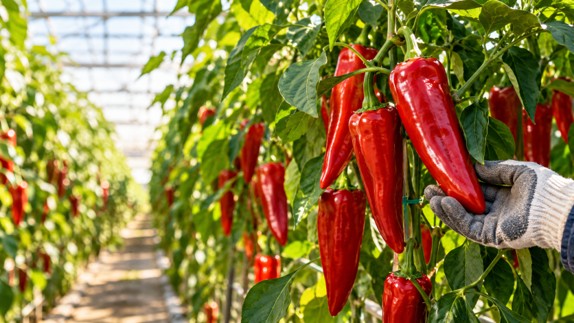
Long-conical peppers are sweet peppers (Capsicum annuum) with a slender, elongated fruit that tapers from a broad shoulder to a narrow point, usually harvested fully red. They belong to the same species as the bell pepper but carry no meaningful heat, so produce buyers place them with sweet red peppers rather than chiles. Their shape is the selling point: a long red pepper reads as premium on the shelf, slices into even rings, and roasts whole without collapsing. Breeders now position long-conical sweet peppers as a gourmet format. BreedX, a seed company specializing in pepper and tomato breeding, describes its long-conical line as sleek and red with intense sweetness, aimed at chefs and at retailers looking for a visual alternative to the standard blocky bell.
For growers the interest is less about looks and more about agronomy. Long peppers are being bred alongside snack and mini formats inside the same seedless sweet pepper programs, which means traits like heat tolerance, yield stability and disease resistance are moving into this shape class quickly. That is what makes the category worth a closer look in 2026, when hotter summers are putting pressure on every pepper crop that relies on reliable fruit set.
Why does heat stress matter so much for long red peppers?
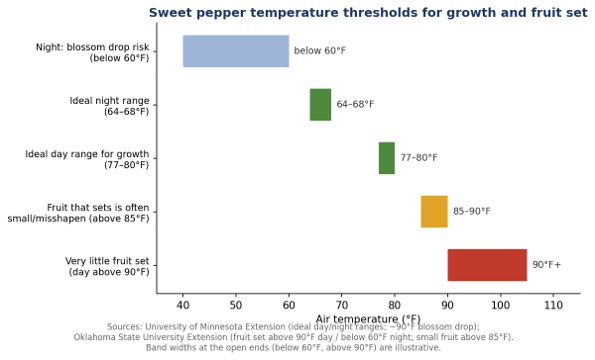
Heat stress matters because pepper flowers fail to set fruit once daytime temperatures pass roughly 90°F (32°C), and fruits that do set above about 85°F tend to be small and poorly shaped. For an elongated pepper, misshapen fruit is a direct loss: a long-conical pepper that sets short, curved or uneven is downgraded even if the plant is healthy. Oklahoma State University’s extension fact sheet on pepper production puts the limits plainly: very little fruit set happens above 90°F during the day or below 60°F at night, and some small-fruited pungent peppers tolerate high-temperature fruit set better than bell types.
The cool end of the range is just as important. Michigan State University Extension notes that night temperatures below 60°F also cause blossom drop, and that a shortage of water at bloom time can produce the same failure. The University of Minnesota Extension gives the ideal window for vegetative growth as 77 to 80°F during the day and 64 to 68°F at night, with blossom and fruit drop appearing near 90°F once plants flower.
Research on Capsicum annuum confirms how narrow the margin is. A 2022 study in the SABRAO Journal of Breeding and Genetics reported that a threshold of about 32.9°C significantly reduced chili pepper production, with heat cutting pollen viability and increasing flower abortion. Pollen development is the weak link: when it fails, the flower drops or the fruit develops unevenly.
How do breeders build heat tolerance into sweet peppers?
Breeders build heat tolerance by selecting lines that keep setting fruit when pollen performance declines, and one of the most effective routes is parthenocarpy, the ability to develop fruit without fertilization. An older Taiwanese study on hot pepper lines found one line that kept a high fruit set at 35/30°C day/night despite low pollen viability, and the researchers suggested parthenocarpy as the likely reason. A plant that does not depend on viable pollen to form fruit is, almost by definition, less exposed to the heat-driven pollen failure described above.
This is the logic behind seedless sweet pepper programs. One breeder of seedless pepper lines bred for heat and cold tolerance says that without seeds inside the fruit, the plant’s energy is redirected to fruit setting, and that its varieties maintain production under high and low temperature extremes and high humidity. The same breeder says all its lines are developed through traditional, non-GMO breeding and supplied to growers as seed rather than seedlings. Those are breeder claims rather than independent trial results, so growers should still test any new long-conical variety in their own climate before scaling.
How do long-conical peppers compare with other sweet pepper formats?
Long-conical peppers sit at the premium, culinary end of the sweet pepper range, while blocky and snack formats cover stuffing, slicing and convenience snacking. The comparison below summarizes how the main formats are typically positioned. Size figures are only given where a breeder has published them.
| Format | Shape and size | Typical use |
| Long-conical | Slender, tapered, elongated red fruit | Gourmet dishes, roasting whole, plated presentation |
| Midi-blocky | Medium-sized, blocky | Stuffing and slicing |
| Mini-kapia | Snack-sized and elongated | Crunchy, sweet snacking |
| 1-bite | 4 to 7 cm, bite-sized | Lunchboxes and whole-fruit snacking |
Within a single seedless program, the long-conical type is often bred to the same standard as the snack types: high yield, tolerance to extreme temperatures and resistance to key plant diseases. The difference is the market it serves. A buyer for a food-service distributor will judge a long pepper on length, straightness and wall color; a snack buyer will judge a mini pepper on crunch, uniformity and pack-out.
When should long-conical peppers be harvested?
Long-conical peppers grown for retail are usually picked at about 90% red color in the morning, or at around 50% color when extra shelf life matters more than full ripeness. That guidance comes from a five-step harvest and post-harvest protocol published for sweet and seedless peppers, which recommends harvesting before 12:00 PM, precooling fruit immediately to 10 to 12°C, and packing into macro- or micro-perforated plastic bags that keep air moving and prevent condensation.
After packing, the same protocol calls for bringing fruit back down to 10°C before transport and keeping an unbroken cool chain to avoid dehydration. Michigan State University Extension gives a similar storage target for peppers: 45 to 50°F with 85 to 90% relative humidity. For an elongated fruit, careful handling also prevents tip breakage and bruising along the narrow end, which shows quickly on a red skin.
Are long red peppers nutritionally different from bell peppers?
Long red peppers are fully ripe sweet peppers, so their nutrition tracks that of ripe red bell peppers, which USDA data puts at 127.7 mg of vitamin C per 100 g raw. Ripening is the main driver: red sweet peppers are ripened green peppers and carry more sugar, which is why long red types taste noticeably sweeter than green ones. Shape itself does not change nutritional value in any documented way, but the long format encourages raw use in salads and as crudités, where vitamin C is preserved because no cooking is involved.
What should growers look for when choosing a long-conical variety?
Growers should prioritize consistent fruit set under their local temperature extremes, uniform length and straightness, and documented disease resistance, in that order. Heat is the most common reason long peppers fail commercially, so a variety’s record in hot-season trials matters more than its appearance in a catalog photo. The University of Minnesota Extension notes that heat-related blossom drop shows up as soon as plants flower in hot weather, which means the first set is where weak varieties are exposed.
Beyond genetics, the same basics apply as for any sweet pepper: steady irrigation through bloom, shade or ventilation to keep canopy temperatures below the 90°F danger zone, and harvest timing matched to the market. A long-conical pepper that is bred to set fruit under stress, picked at the right color and cooled quickly is the format’s best case: a premium red pepper that holds its shape from the greenhouse to the plate.
Frequently Asked Questions
Are long-conical peppers spicy?
No, long-conical peppers are sweet peppers in the species Capsicum annuum and are bred for sweetness rather than heat.
What temperature stops pepper plants from setting fruit?
Pepper fruit set drops sharply when daytime temperatures exceed about 90°F (32°C) or night temperatures fall below 60°F (16°C).
How should long red peppers be stored after harvest?
Long red peppers keep best when cooled quickly after picking and stored at about 45 to 50°F (7 to 10°C) with 85 to 90% relative humidity.
Why are some sweet peppers bred to be seedless?
Seedless sweet peppers are bred for convenience and, according to breeders, because a plant that does not invest energy in seeds can direct more of it to setting fruit.

|
Key Takeaways
|
What is a venture capital fund, in plain terms?
A venture capital fund is a pool of capital, contributed by investors and managed by a dedicated investment team, used to fund private companies, typically early-stage or growth-stage businesses with high growth potential, in exchange for an equity ownership stake. Unlike a bank loan, venture capital doesn’t need to be repaid on a fixed schedule; instead, the fund’s investors participate in the company’s future upside (or downside) alongside its founders. The fund’s managers, often called general partners, make the actual investment decisions on behalf of the fund’s investors, who are typically called limited partners.
How is a typical VC fund actually structured?
The overwhelming majority of venture capital funds are structured as limited partnerships. General partners (GPs) manage the fund, source and evaluate investment opportunities, sit on portfolio company boards, and make the calls about which companies to fund and when to exit. Limited partners (LPs), which can include pension funds, university endowments, family offices, and wealthy individuals, commit capital to the fund but generally aren’t involved in individual investment decisions. In exchange for their capital, LPs typically pay the fund a management fee, often around 2% of committed capital annually, plus a share of the fund’s profits, commonly 20%, known as carried interest.
What does a VC fund’s lifecycle actually look like?
A traditional VC fund isn’t a permanent, evergreen pool of capital; it has a defined lifecycle, typically spanning 8 to 12 years from first close to final wind-down.
| Fund lifecycle stage | What actually happens |
|---|---|
| Fundraising and first close | The fund raises committed capital from LPs before making its first investments. |
| Investment period | Typically the first 3 to 5 years, during which the fund makes its initial investments into portfolio companies. |
| Active management and follow-on | The fund supports existing portfolio companies, often participating in follow-on funding rounds as those companies grow. |
| Exit and distribution | The fund realizes returns through acquisitions, IPOs, or other exit events, and distributes proceeds back to LPs. |
How large has the global venture capital market actually become?
The scale of capital flowing through venture capital funds globally has grown enormously over the past two decades. IMARC Group’s venture capital investment market analysis values the global market at $284.8 billion in 2023, projected to reach $1,310.8 billion by 2032, a compound annual growth rate of 17.9%. That growth reflects the increasing role venture capital plays in fostering innovation and entrepreneurship globally, with software consistently commanding the largest share of capital deployed, and follow-on funding, capital deployed into companies a fund has already backed, generally outpacing first-time venture funding.
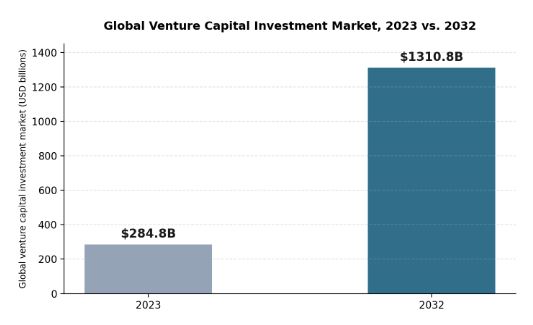
Global venture capital investment market size, 2023 versus 2032, according to IMARC Group.
Are all venture capital funds structured the same way?
No, and understanding the alternatives matters for founders evaluating which type of investor actually fits their company. Elron Ventures’ own description of its model illustrates one such alternative directly: rather than a traditional limited partnership raising committed capital from external LPs, Elron operates as a publicly traded technology investment company, one of Israel’s leading investment firms since 1961, deploying capital through two core growth engines, early-growth technology investments and an M&A-driven growth strategy focused on acquiring early-stage dual-use technology companies. That structure gives a company like Elron more flexibility in its investment horizon and capital deployment than a fund bound by a fixed limited-partnership lifecycle, since it isn’t operating against the same fundraising and wind-down clock a traditional 8-to-12-year fund faces.
What does ‘early-growth’ investing actually mean, as distinct from seed or late-stage?
Venture capital funds typically specialize by stage, and the terminology matters for founders trying to identify the right fit. Seed-stage funds back companies at their earliest, often pre-revenue stage, when the primary risk being underwritten is whether the founding team and product concept can find genuine traction. Early-growth investing, the stage many established Israeli VC funds focus on, targets companies that have already demonstrated initial product-market fit and are looking to scale that traction into a larger, more durable business. Late-stage and growth-equity funds, by contrast, back companies with established revenue and a clearer path to an exit event, often writing much larger checks at higher valuations. A fund’s stated stage focus should shape which companies actually approach it for funding, since a seed-stage pitch to a late-stage growth fund, or vice versa, rarely leads anywhere productive.
What should a founder actually understand before approaching a VC fund?
- What stage does the fund actually invest at? Confirm this matches your company’s current stage before spending time on outreach.
- What sectors or technologies does the fund focus on? Many funds specialize deeply, and a fund’s public messaging usually signals this clearly.
- Does the fund lead rounds, or only participate alongside a lead investor? This affects how much capital and support you can expect from that single relationship.
- What does the fund actually offer beyond capital? Strategic partnerships, sector expertise, and portfolio company networks can matter as much as the check size itself.
How does a VC fund actually decide when to exit an investment?
Exit timing is rarely a unilateral decision made purely on a fund’s own schedule; it emerges from a mix of the portfolio company’s own trajectory, market conditions, and the fund’s own lifecycle pressure. A fund nearing the end of its stated term has real incentive to push toward a liquidity event, an acquisition or IPO, since its own LPs expect distributions within a reasonably predictable timeframe rather than an indefinite hold. At the same time, a fund that exits too early can leave significant value on the table if a portfolio company’s growth trajectory was only just accelerating. Board seats, which many VC funds negotiate as part of their investment terms, give fund managers a formal voice in these exit timing conversations, rather than leaving the decision entirely in founders’ hands.
What does ‘dry powder’ actually mean, and why does it matter for founders?
Dry powder refers to capital that investors have already committed to a fund but that the fund hasn’t yet deployed into portfolio companies. A large pool of dry powder sitting across a market’s VC funds is generally a positive signal for founders, since it suggests real capital is available and actively looking for a home, rather than funds having already committed most of their capacity to existing portfolio companies. That said, dry powder alone doesn’t guarantee a fund will actually write a check to any particular startup; it simply describes the scale of capital theoretically available, not how selectively or aggressively any specific fund is currently deploying it.
Frequently Asked Questions
What’s the difference between a general partner and a limited partner?
General partners (GPs) manage the venture capital fund, make investment decisions, and typically earn management fees and a share of profits (carried interest). Limited partners (LPs) contribute capital to the fund but aren’t involved in day-to-day investment decisions.
How long does a typical venture capital fund actually last?
Most traditional VC funds have a lifecycle of 8 to 12 years, covering an investment period, an active management and follow-on period, and an exit and distribution period, though extensions are common when portfolio companies need more time to reach an exit event.
Can a venture capital fund invest in a company more than once?
Yes, this is common and is typically referred to as follow-on investment, where a fund participates in later funding rounds of a company it has already backed, often to maintain its ownership percentage as the company raises additional capital.
Is a publicly traded technology investment company the same thing as a traditional VC fund?
Not exactly. A publicly traded technology investment company, like Elron Ventures, typically deploys its own balance sheet capital rather than raising committed capital from external limited partners, giving it a different capital structure and investment horizon than a traditional limited partnership fund.
| Key Takeaways
• Israeli tech companies raised roughly $3.1 billion across 98 rounds in Q1 2026, up 34% year over year, with foreign investors supplying 65.9% of that capital. • Cybersecurity accounted for about 40% of Israeli VC funding in Q1 2026, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period. • Some Israeli VC firms operate a standard direct-investment fund alongside a separate joint-venture or acquisition arm focused on a specific sector, such as defense technology. • Government co-investment programs dating back to the early 1990s helped seed Israel’s venture capital industry, contributing to a market that now supports many independently capitalized local funds. |
What makes Israeli venture capital firms operate differently from international investors?
Israeli venture capital firms tend to combine a deep local sourcing network in a small, densely connected tech ecosystem with an operating assumption that most portfolio companies will need to scale into markets, most commonly the US and Europe, from day one. That dual-market posture shows up structurally, not just in messaging. one firm’s public profile of its own history and philosophy describes decisions made “within days to a few weeks,” a pace that reflects how tightly connected the local investor and founder community is compared with larger, more geographically dispersed markets.
How large is Israel’s venture capital market right now?
Israeli tech companies raised about $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase year over year, with March 2026 alone accounting for roughly $1.2 billion of that total. Foreign investors supplied 65.9% of that capital, underscoring how dependent the local ecosystem is on international capital even as local firms do much of the early sourcing and structuring. Cybersecurity alone accounted for about 40% of funds raised in the quarter, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period, a reminder of how quickly sector allocation can shift.
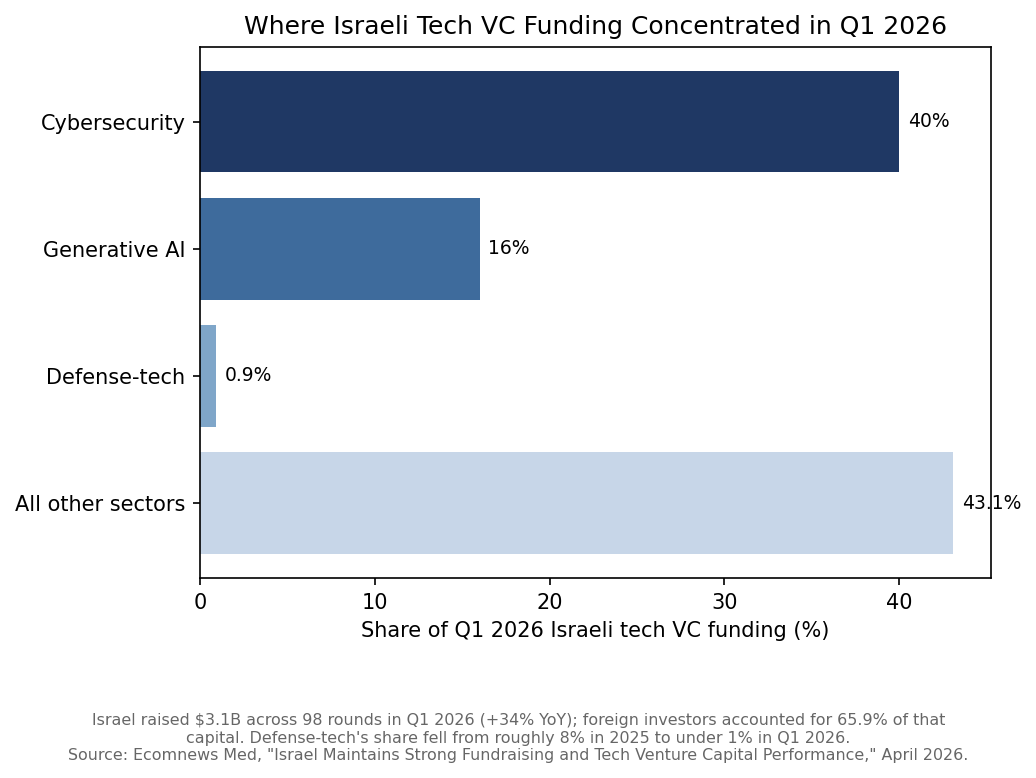
Sector breakdown of Israeli tech venture capital funding in Q1 2026, based on Ecomnews Med’s April 2026 reporting.
Why do some Israeli VC firms invest through more than one structure?
Some firms pair a standard direct-investment fund with a separate acquisition or joint-venture arm aimed at a specific sector, which lets them play both an early investor role and a strategic consolidator role in the same market. a portfolio spanning cybersecurity, deep and defense tech, medical devices, and enterprise software shows what that breadth looks like in practice, with more than 70 companies represented across active and exited positions. A defense-technology joint venture built with an established strategic partner is one example of this second structure, sitting alongside the firm’s conventional early-growth fund rather than replacing it.
How does sector specialization show up inside a single Israeli VC portfolio?
Sector specialization inside Israeli VC portfolios usually shows up as dedicated teams or sub-funds for a firm’s strongest local sourcing advantage, most often cybersecurity, layered underneath a broader generalist mandate. a dedicated cybersecurity portfolio segment and a medical-device investing track record spanning cardiovascular, orthopedic, and diagnostic devices illustrate two very different specializations coexisting inside the same firm, each drawing on a different regulatory and go-to-market path.
What role does government policy play in Israel’s VC ecosystem?
A government-funded program launched in 1993 played a documented role in seeding Israel’s venture capital industry by matching private investment at a set ratio, rather than by investing directly on its own. Under that program, the government allocated $100 million in total, $80 million of which matched foreign and domestic investment at roughly a 40% ratio so outside firms could establish their own funds inside Israel, with most of those funds later repurchasing the government’s stake within five years. See a historical summary of that matching-fund program and its transition to private ownership in 1997 for how that early policy groundwork is one reason the ecosystem now supports many independently capitalized local funds rather than depending on a handful of foreign offices, even though foreign capital still supplies the majority of dollars invested today.
Frequently Asked Questions
How much venture capital did Israeli tech companies raise in Q1 2026?
Israeli tech companies raised approximately $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase compared with the same period the year before.
What share of Israeli VC funding comes from foreign investors?
Foreign investors accounted for about 65.9% of total Israeli tech venture capital funding in Q1 2026, according to Ecomnews Med’s reporting.
Which sector attracted the most Israeli VC funding in early 2026?
Cybersecurity attracted the largest share, accounting for roughly 40% of total Israeli tech VC funding in the first quarter of 2026.
Do Israeli VC firms only invest in Israeli companies?
No, many Israeli VC firms invest with an explicit assumption that portfolio companies will expand into international markets, most commonly the United States and Europe, from an early stage.
מבוא
שוק הבנייה הישראלי עומד בפני שינוי מבני מואץ. לחצי עלות, מחסור בכוח אדם מיומן, עליות בחומרי גלם וגידול בביקוש לדיור – כל אלה מאלצים חברות בנייה לחפש יעילות מקומות שלא חיפשו קודם. הפתרון מגיע מהטכנולוגיה. בשנת 2025, חמש טכנולוגיות עומדות במרכז הטרנספורמציה הדיגיטלית של הענף – וחברות שמאמצות אותן מוקדם יותר יהנו מיתרון תחרותי משמעותי. ConWize היא דוגמה לפלטפורמה ישראלית שמשלבת כמה מהכלים הללו – אומדן, תמחור וניהול מכרזים – בפתרון אחד מאוחד, שנבנה על הצרכים הספציפיים של שוק הבנייה המקומי.
טכנולוגיה 1: BIM – מידול מידע לבניין
BIM (Building Information Modeling) אינה עוד חידוש – היא הופכת לסטנדרט עבודה. BIM מאפשרת יצירת מודל תלת-ממדי דיגיטלי של הבניין שכולל לא רק גיאומטריה אלא גם נתוני עלות, לוחות זמנים, מפרטים טכניים ותחזוקה עתידית.
אנגליה מחייבת BIM בכל מבנה ציבורי מ-2016
ישראל צפויה להרחיב דרישות BIM בפרויקטי תשתיות ממשלתיים ב-2025–2026
חיסכון ממוצע: 5–10% בעלויות בנייה, 20% בשגיאות תכנוני
טכנולוגיה 2: ניהול אומדן ותמחור בענן
גיליונות Excel אינם מספיקים יותר כשמנהלים מספר פרויקטים מורכבים בו-זמנית. פתרונות ענן לאומדן מאפשרים גישה בכל מקום, שיתוף פעולה בזמן אמת ועדכון מחירים אוטומטי. פלטפורמת ConWize לאומדן ותמחור מייצגת את הדור הבא של כלים אלה: ממשק עברי, כתב כמויות מובנה, ניהול מכרזים ושליטה בתקציב – הכל מקום אחד.
חיסכון ממוצע בזמן אומדן: 35–50%
ירידה בשגיאות תמחור: עד 70%
זמינות מהשטח: עדכון ומעקב ישירות מהסמארטפון
טכנולוגיה 3: פלטפורמות ניהול פרויקטים בענן
כלים כמו Procore, PlanGrid ומקבילות ישראליות מאפשרות ניהול לוחות זמנים, עבודות וחוזים מרכזי – עם ניראות מלאה לכל בעלי העניין בפרויקט. לפי Dodge Data & Analytics, חברות שמשתמשות בפלטפורמות ניהול פרויקטים מדווחות על עמידה בלוחות זמנים גבוהה ב-30% לעומת חברות שאינן משתמשות.
ניהול RFI ותוכניות ישירות מהאפליקציה
תיעוד אוטומטי של כל החלטה ואירוע בשטח
דשבורד סטטוס לכל קבלן ומשימה
טכנולוגיה 4: ניתוח נתוני שטח ו-IoT
חיישנים, מצלמות ומכשירי IoT שמוצבים באתר הבנייה מאפשרים מעקב בזמן אמת אחר התקדמות עבודות, שימוש בציוד ותנאי בטיחות. הנתונים מוזנים לפלטפורמות ניתוח שמאפשרות לזהות עיכובים, בזבוז ומפגעי בטיחות לפני שהם הופכים לבעיות.
ניטור ממשי של שעות עבודה ונוכחות
מעקב GPS אחר ציוד וכלי רכב
התראות בטיחות אוטומטיות
טכנולוגיה 5: בינה מלאכותית לתמחור ואומדן
הדור הבא של כלי האומדן משלב בינה מלאכותית שמנתחת פרויקטים קודמים ומחירי שוק כדי לייצר אומדנים מדויקים יותר. מערכות AI מסוגלות לזהות חריגות, להצביע על סיכוני עלות ולהציע חלופות תכנוניות זולות יותר – כל זאת בשבריר מהזמן שצוות אנושי היה זקוק לו.
לפי סקר Autodesk מ-2024, 68% ממנהלי הפרויקטים בעולם מאמינים ש-AI תהיה מרכזית בתמחור ואומדן תוך שלוש שנים.
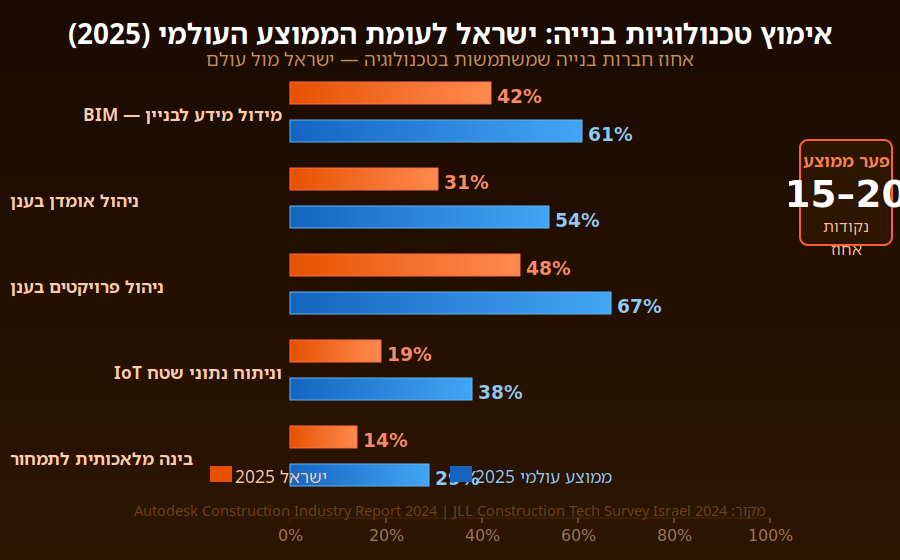
טבלת השוואה: שיעורי אימוץ טכנולוגיות בנייה בישראל (2025)
| טכנולוגיה | שיעור אימוץ (ישראל) | שיעור אימוץ (עולמי) |
| BIM | 42% | 61% |
| ניהול אומדן בענן | 31% | 54% |
| ניהול פרויקטים בענן | 48% | 67% |
| IoT וניתוח שטח | 19% | 38% |
| AI לתמחור ואומדן | 14% | 29% |
מקור: Autodesk Construction Industry Report 2024; JLL Construction Tech Survey Israel 2024
מה שוק הבנייה בישראלי צריך לדעת
ישראל מאמצת טכנולוגיות בנייה בקצב איטי יותר מהממוצע העולמי – אך הפער מצטמצם. הנהגת מחייבת BIM בפרויקטים ציבוריים, עלייה בהיקפי הבנייה ותחרות גוברת על כוח אדם מיומן יוצרים לחץ שמאיץ את קצב האימוץ. חברות שיתחילו את המעבר הדיגיטלי עכשיו ייהנו מיתרון ראשון-מגיע שיהיה קשה לשחזר בעוד שלוש שנים.
התחילו בכלי ה-ROI המהיר ביותר: ניהול אומדן ותמחור דיגיטלי
צרו מסד נתונים פנימי של עלויות מפרויקטים קודמים
השקיעו בהכשרת צוות – הטכנולוגיה טובה בדיוק כמו האנשים שמשתמשים בה
בחרו פלטפורמה עם תמיכה מקומית ותיעוד בעברית
סיכום
הטרנספורמציה הדיגיטלית של שוק הבנייה הישראלי אינה שאלה של ‘אם’ אלא של ‘מתי’. הכלים שפעם היו נחלת חברות הבנייה הגדולות ביותר בעולם הפכו נגישים, מותאמים מקומית ומוכחים בשטח. חברות שישכילו לאמץ טכנולוגיות אלה יוכלו לנהל פרויקטים מורכבים יותר, לשמור על שולי רווח בריאים ולספק ללקוחות שלהן רמת מקצועיות שהמתחרים לא יוכלו להציע. זהו הרגע לפעול

Should B2B Brands Optimize for Specific AI Engines? How ChatGPT, Google, Perplexity, and Claude Compare

What Is a Blow Molded Case? Process, Materials and Trade-offs Explained

Delay Lines Compared: Coaxial, Acoustic, Digital and Fiber Optic Options for RF Systems

-
 Business Solutions2 years ago
Live Video Broadcasting with Bonded Transmission Technology
-
 Business Solutions1 year ago
The Future of Healthcare SMS and RCS Messaging
-
 Business Solutions2 years ago
2-Way Texting Solutions from Company Message Services
-
 Business Solutions2 years ago
Communication with Analog to Fiber Converters & RF Link Budgets
-
 DSRC Communication2 years ago
The Crossroads of Connectivity: DSRC vs. C-V2X Technologies in Automotive Communication
-
 Business Solutions2 years ago
Wholesale SMS Platforms with OTP Services
-
 Business Solutions2 years ago
Choosing the Right B2B Digital Marketing Agency: A Guide
-
 3D Technology2 years ago
How Multispectral Cameras Advance Book Scanning