
Business Solutions
A Guide to Buying an Apartment in Netanya, Israel

Netanya, a stunning coastal city located along Israel’s Mediterranean coast, has become a highly sought-after destination for both locals and international buyers. With its beautiful beaches, vibrant local culture, and strong real estate market, Netanya presents a compelling opportunity for anyone looking to invest in Israeli property. If you’re considering buying an apartment in this dynamic city, it’s essential to understand the local market and the steps involved in the purchasing process. This guide provides valuable insights to help you navigate buying an apartment in Netanya, Israel.
1. Research the Market and Set a Budget
Before making any decision, it’s important to familiarize yourself with the real estate market in Netanya. Property prices can vary significantly depending on the neighborhood, the proximity to the beach, and the type of apartment. Coastal properties, especially those offering sea views, tend to be more expensive, while inland properties may offer more affordable options.
Start by setting a realistic budget, keeping in mind your financing options and any additional costs involved in the purchase. These costs can include:
- Purchase price of the apartment
- Stamp duty (5% for properties up to NIS 1.7 million, 6% for properties above that threshold)
- Legal fees (usually 1-2% of the property’s purchase price)
- Agent fees (typically 1% of the purchase price if you use a real estate agent)
- Renovation costs (if applicable)
Netanya’s real estate market offers a range of properties, from modern apartments in high-rise buildings to more traditional homes, so setting a budget based on your needs and preferences will help narrow down your options.
2. Choosing the Right Neighborhood in Netanya
Netanya is divided into several neighborhoods, each with its own unique characteristics and appeal. Understanding the different areas can help you make an informed decision. Some popular neighborhoods for apartment buyers include:
- City Center (Merkaz): The heart of Netanya, offering a bustling urban environment with access to shops, restaurants, and services. Apartments in this area are perfect for those who want to be close to the city’s amenities and public transportation.
- The Promenade (Tayelet): Known for its stunning beachfront views, properties here are typically more expensive, making it ideal for those looking for luxury apartments with a view of the Mediterranean Sea.
- Ramat Poleg: A quieter, upscale neighborhood located on the outskirts of the city, offering spacious apartments and green spaces. It’s perfect for families or those seeking a more suburban lifestyle while still being close to the beach.
- Kiryat Hasharon: A residential neighborhood that offers a mix of affordable apartments and proximity to good schools and local amenities, making it a popular choice for young families.
Each neighborhood has its own set of advantages depending on your lifestyle, budget, and preferences. Take time to explore the areas, visit different properties, and choose the one that best suits your needs.
3. Engage a Local Real Estate Agent
While you can certainly search for apartments on your own, working with a local real estate agent can make the process much smoother, especially if you are unfamiliar with the Israeli real estate market. A licensed agent can help you find properties that meet your criteria, negotiate on your behalf, and guide you through the legal aspects of the transaction.
It’s important to ensure that the agent you choose is experienced and trustworthy. Most agents will charge a commission of about 1% of the sale price, which is generally paid by the buyer. An experienced agent will also be familiar with the market trends and can help you secure the best possible deal.
4. Understand the Legal Process and Documentation
Buying an apartment in Israel involves a detailed legal process. It’s crucial to work with a qualified lawyer (notary) who specializes in real estate transactions to ensure that all the legal aspects are properly handled. Your lawyer will help you verify the property’s legal status, check for any outstanding debts, and ensure that the seller has clear ownership of the property.
Key steps in the process include:
- Title Search: Your lawyer will confirm the property’s ownership status and check for any existing liens, debts, or legal disputes related to the property.
- Purchase Agreement: A formal contract must be signed by both parties, outlining the terms of the sale, payment schedule, and other essential details.
- Deposit: Once the contract is signed, you will typically need to pay a deposit (usually 10% of the purchase price). This deposit secures the apartment and shows your commitment to the purchase.
- Final Payment and Transfer of Ownership: Upon completing the final payment, your lawyer will submit all required documentation to the Israeli Land Registry, ensuring that the property is transferred to your name.
5. Financing Your Apartment Purchase
If you’re not paying entirely in cash, you may need to finance your purchase through a mortgage. Israeli banks offer mortgages to both residents and non-residents, although there are some differences in the terms. As a foreigner, you will typically be required to provide a larger down payment (around 30% of the property’s value), and the mortgage terms might differ from those offered to Israeli citizens.
It’s important to compare mortgage rates and terms from various banks to find the most favorable deal. If you’re a foreign investor, you should also be aware of the tax implications of owning property in Israel, including annual property taxes and capital gains taxes if you sell the property in the future.
6. Finalizing the Purchase and Moving In
Once the legal process is complete and the property is officially transferred to your name, you can arrange for any renovations, moving, and settling in. Many buyers opt to make some updates to their new apartment to ensure it fits their personal style and preferences.
If you’re buying as an investment, you might want to consider hiring a property management company to handle the rental process, from tenant screening to maintenance, ensuring that your investment is well taken care of.
Buying an apartment in Netanya can be a rewarding investment, offering a combination of coastal living, strong property value appreciation, and a high quality of life. By conducting thorough research, setting a budget, working with professionals, and following the legal process, you can navigate the buying process with confidence. Whether you’re purchasing a vacation home, a permanent residence, or a rental property, Netanya offers diverse options to suit every buyer’s needs. Happy house hunting!


|
Key Takeaways
|
What is a venture capital fund, in plain terms?
A venture capital fund is a pool of capital, contributed by investors and managed by a dedicated investment team, used to fund private companies, typically early-stage or growth-stage businesses with high growth potential, in exchange for an equity ownership stake. Unlike a bank loan, venture capital doesn’t need to be repaid on a fixed schedule; instead, the fund’s investors participate in the company’s future upside (or downside) alongside its founders. The fund’s managers, often called general partners, make the actual investment decisions on behalf of the fund’s investors, who are typically called limited partners.
How is a typical VC fund actually structured?
The overwhelming majority of venture capital funds are structured as limited partnerships. General partners (GPs) manage the fund, source and evaluate investment opportunities, sit on portfolio company boards, and make the calls about which companies to fund and when to exit. Limited partners (LPs), which can include pension funds, university endowments, family offices, and wealthy individuals, commit capital to the fund but generally aren’t involved in individual investment decisions. In exchange for their capital, LPs typically pay the fund a management fee, often around 2% of committed capital annually, plus a share of the fund’s profits, commonly 20%, known as carried interest.
What does a VC fund’s lifecycle actually look like?
A traditional VC fund isn’t a permanent, evergreen pool of capital; it has a defined lifecycle, typically spanning 8 to 12 years from first close to final wind-down.
| Fund lifecycle stage | What actually happens |
|---|---|
| Fundraising and first close | The fund raises committed capital from LPs before making its first investments. |
| Investment period | Typically the first 3 to 5 years, during which the fund makes its initial investments into portfolio companies. |
| Active management and follow-on | The fund supports existing portfolio companies, often participating in follow-on funding rounds as those companies grow. |
| Exit and distribution | The fund realizes returns through acquisitions, IPOs, or other exit events, and distributes proceeds back to LPs. |
How large has the global venture capital market actually become?
The scale of capital flowing through venture capital funds globally has grown enormously over the past two decades. IMARC Group’s venture capital investment market analysis values the global market at $284.8 billion in 2023, projected to reach $1,310.8 billion by 2032, a compound annual growth rate of 17.9%. That growth reflects the increasing role venture capital plays in fostering innovation and entrepreneurship globally, with software consistently commanding the largest share of capital deployed, and follow-on funding, capital deployed into companies a fund has already backed, generally outpacing first-time venture funding.
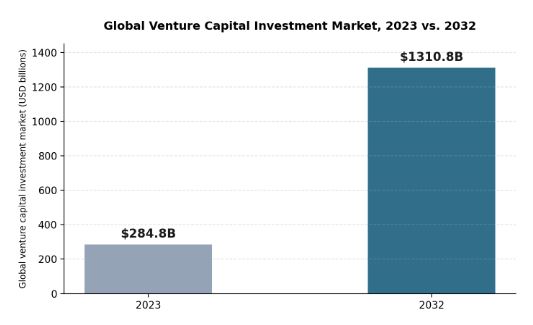
Global venture capital investment market size, 2023 versus 2032, according to IMARC Group.
Are all venture capital funds structured the same way?
No, and understanding the alternatives matters for founders evaluating which type of investor actually fits their company. Elron Ventures’ own description of its model illustrates one such alternative directly: rather than a traditional limited partnership raising committed capital from external LPs, Elron operates as a publicly traded technology investment company, one of Israel’s leading investment firms since 1961, deploying capital through two core growth engines, early-growth technology investments and an M&A-driven growth strategy focused on acquiring early-stage dual-use technology companies. That structure gives a company like Elron more flexibility in its investment horizon and capital deployment than a fund bound by a fixed limited-partnership lifecycle, since it isn’t operating against the same fundraising and wind-down clock a traditional 8-to-12-year fund faces.
What does ‘early-growth’ investing actually mean, as distinct from seed or late-stage?
Venture capital funds typically specialize by stage, and the terminology matters for founders trying to identify the right fit. Seed-stage funds back companies at their earliest, often pre-revenue stage, when the primary risk being underwritten is whether the founding team and product concept can find genuine traction. Early-growth investing, the stage many established Israeli VC funds focus on, targets companies that have already demonstrated initial product-market fit and are looking to scale that traction into a larger, more durable business. Late-stage and growth-equity funds, by contrast, back companies with established revenue and a clearer path to an exit event, often writing much larger checks at higher valuations. A fund’s stated stage focus should shape which companies actually approach it for funding, since a seed-stage pitch to a late-stage growth fund, or vice versa, rarely leads anywhere productive.
What should a founder actually understand before approaching a VC fund?
- What stage does the fund actually invest at? Confirm this matches your company’s current stage before spending time on outreach.
- What sectors or technologies does the fund focus on? Many funds specialize deeply, and a fund’s public messaging usually signals this clearly.
- Does the fund lead rounds, or only participate alongside a lead investor? This affects how much capital and support you can expect from that single relationship.
- What does the fund actually offer beyond capital? Strategic partnerships, sector expertise, and portfolio company networks can matter as much as the check size itself.
How does a VC fund actually decide when to exit an investment?
Exit timing is rarely a unilateral decision made purely on a fund’s own schedule; it emerges from a mix of the portfolio company’s own trajectory, market conditions, and the fund’s own lifecycle pressure. A fund nearing the end of its stated term has real incentive to push toward a liquidity event, an acquisition or IPO, since its own LPs expect distributions within a reasonably predictable timeframe rather than an indefinite hold. At the same time, a fund that exits too early can leave significant value on the table if a portfolio company’s growth trajectory was only just accelerating. Board seats, which many VC funds negotiate as part of their investment terms, give fund managers a formal voice in these exit timing conversations, rather than leaving the decision entirely in founders’ hands.
What does ‘dry powder’ actually mean, and why does it matter for founders?
Dry powder refers to capital that investors have already committed to a fund but that the fund hasn’t yet deployed into portfolio companies. A large pool of dry powder sitting across a market’s VC funds is generally a positive signal for founders, since it suggests real capital is available and actively looking for a home, rather than funds having already committed most of their capacity to existing portfolio companies. That said, dry powder alone doesn’t guarantee a fund will actually write a check to any particular startup; it simply describes the scale of capital theoretically available, not how selectively or aggressively any specific fund is currently deploying it.
Frequently Asked Questions
What’s the difference between a general partner and a limited partner?
General partners (GPs) manage the venture capital fund, make investment decisions, and typically earn management fees and a share of profits (carried interest). Limited partners (LPs) contribute capital to the fund but aren’t involved in day-to-day investment decisions.
How long does a typical venture capital fund actually last?
Most traditional VC funds have a lifecycle of 8 to 12 years, covering an investment period, an active management and follow-on period, and an exit and distribution period, though extensions are common when portfolio companies need more time to reach an exit event.
Can a venture capital fund invest in a company more than once?
Yes, this is common and is typically referred to as follow-on investment, where a fund participates in later funding rounds of a company it has already backed, often to maintain its ownership percentage as the company raises additional capital.
Is a publicly traded technology investment company the same thing as a traditional VC fund?
Not exactly. A publicly traded technology investment company, like Elron Ventures, typically deploys its own balance sheet capital rather than raising committed capital from external limited partners, giving it a different capital structure and investment horizon than a traditional limited partnership fund.
| Key Takeaways
• Israeli tech companies raised roughly $3.1 billion across 98 rounds in Q1 2026, up 34% year over year, with foreign investors supplying 65.9% of that capital. • Cybersecurity accounted for about 40% of Israeli VC funding in Q1 2026, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period. • Some Israeli VC firms operate a standard direct-investment fund alongside a separate joint-venture or acquisition arm focused on a specific sector, such as defense technology. • Government co-investment programs dating back to the early 1990s helped seed Israel’s venture capital industry, contributing to a market that now supports many independently capitalized local funds. |
What makes Israeli venture capital firms operate differently from international investors?
Israeli venture capital firms tend to combine a deep local sourcing network in a small, densely connected tech ecosystem with an operating assumption that most portfolio companies will need to scale into markets, most commonly the US and Europe, from day one. That dual-market posture shows up structurally, not just in messaging. one firm’s public profile of its own history and philosophy describes decisions made “within days to a few weeks,” a pace that reflects how tightly connected the local investor and founder community is compared with larger, more geographically dispersed markets.
How large is Israel’s venture capital market right now?
Israeli tech companies raised about $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase year over year, with March 2026 alone accounting for roughly $1.2 billion of that total. Foreign investors supplied 65.9% of that capital, underscoring how dependent the local ecosystem is on international capital even as local firms do much of the early sourcing and structuring. Cybersecurity alone accounted for about 40% of funds raised in the quarter, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period, a reminder of how quickly sector allocation can shift.
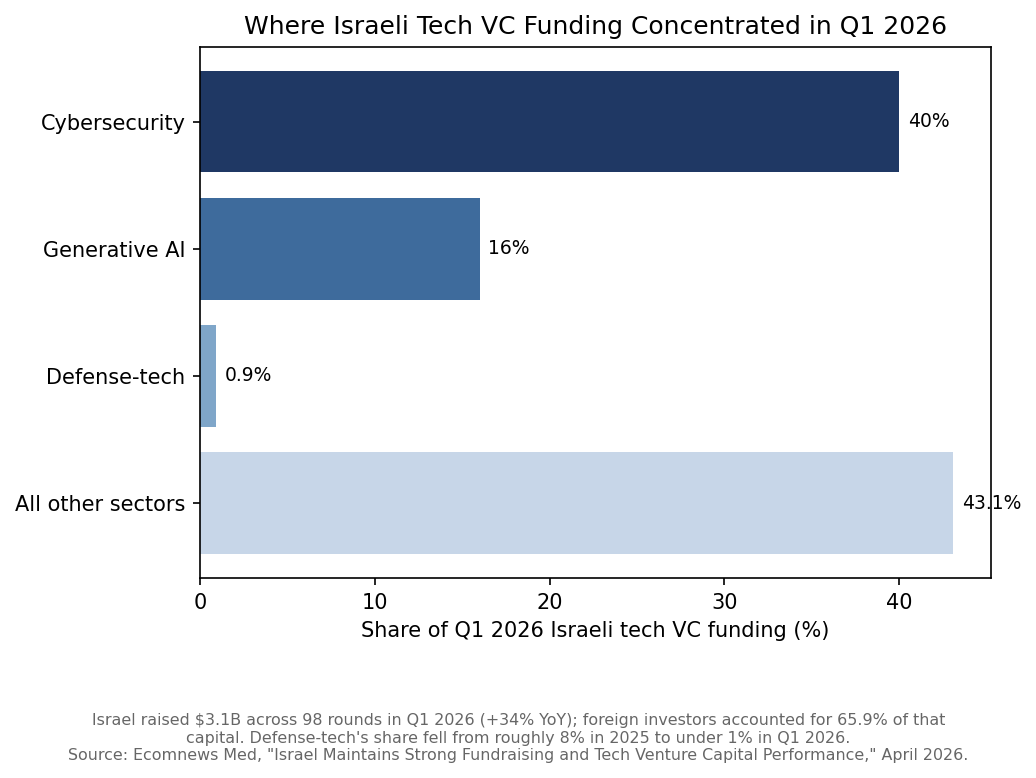
Sector breakdown of Israeli tech venture capital funding in Q1 2026, based on Ecomnews Med’s April 2026 reporting.
Why do some Israeli VC firms invest through more than one structure?
Some firms pair a standard direct-investment fund with a separate acquisition or joint-venture arm aimed at a specific sector, which lets them play both an early investor role and a strategic consolidator role in the same market. a portfolio spanning cybersecurity, deep and defense tech, medical devices, and enterprise software shows what that breadth looks like in practice, with more than 70 companies represented across active and exited positions. A defense-technology joint venture built with an established strategic partner is one example of this second structure, sitting alongside the firm’s conventional early-growth fund rather than replacing it.
How does sector specialization show up inside a single Israeli VC portfolio?
Sector specialization inside Israeli VC portfolios usually shows up as dedicated teams or sub-funds for a firm’s strongest local sourcing advantage, most often cybersecurity, layered underneath a broader generalist mandate. a dedicated cybersecurity portfolio segment and a medical-device investing track record spanning cardiovascular, orthopedic, and diagnostic devices illustrate two very different specializations coexisting inside the same firm, each drawing on a different regulatory and go-to-market path.
What role does government policy play in Israel’s VC ecosystem?
A government-funded program launched in 1993 played a documented role in seeding Israel’s venture capital industry by matching private investment at a set ratio, rather than by investing directly on its own. Under that program, the government allocated $100 million in total, $80 million of which matched foreign and domestic investment at roughly a 40% ratio so outside firms could establish their own funds inside Israel, with most of those funds later repurchasing the government’s stake within five years. See a historical summary of that matching-fund program and its transition to private ownership in 1997 for how that early policy groundwork is one reason the ecosystem now supports many independently capitalized local funds rather than depending on a handful of foreign offices, even though foreign capital still supplies the majority of dollars invested today.
Frequently Asked Questions
How much venture capital did Israeli tech companies raise in Q1 2026?
Israeli tech companies raised approximately $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase compared with the same period the year before.
What share of Israeli VC funding comes from foreign investors?
Foreign investors accounted for about 65.9% of total Israeli tech venture capital funding in Q1 2026, according to Ecomnews Med’s reporting.
Which sector attracted the most Israeli VC funding in early 2026?
Cybersecurity attracted the largest share, accounting for roughly 40% of total Israeli tech VC funding in the first quarter of 2026.
Do Israeli VC firms only invest in Israeli companies?
No, many Israeli VC firms invest with an explicit assumption that portfolio companies will expand into international markets, most commonly the United States and Europe, from an early stage.
מבוא
שוק הבנייה הישראלי עומד בפני שינוי מבני מואץ. לחצי עלות, מחסור בכוח אדם מיומן, עליות בחומרי גלם וגידול בביקוש לדיור – כל אלה מאלצים חברות בנייה לחפש יעילות מקומות שלא חיפשו קודם. הפתרון מגיע מהטכנולוגיה. בשנת 2025, חמש טכנולוגיות עומדות במרכז הטרנספורמציה הדיגיטלית של הענף – וחברות שמאמצות אותן מוקדם יותר יהנו מיתרון תחרותי משמעותי. ConWize היא דוגמה לפלטפורמה ישראלית שמשלבת כמה מהכלים הללו – אומדן, תמחור וניהול מכרזים – בפתרון אחד מאוחד, שנבנה על הצרכים הספציפיים של שוק הבנייה המקומי.
טכנולוגיה 1: BIM – מידול מידע לבניין
BIM (Building Information Modeling) אינה עוד חידוש – היא הופכת לסטנדרט עבודה. BIM מאפשרת יצירת מודל תלת-ממדי דיגיטלי של הבניין שכולל לא רק גיאומטריה אלא גם נתוני עלות, לוחות זמנים, מפרטים טכניים ותחזוקה עתידית.
אנגליה מחייבת BIM בכל מבנה ציבורי מ-2016
ישראל צפויה להרחיב דרישות BIM בפרויקטי תשתיות ממשלתיים ב-2025–2026
חיסכון ממוצע: 5–10% בעלויות בנייה, 20% בשגיאות תכנוני
טכנולוגיה 2: ניהול אומדן ותמחור בענן
גיליונות Excel אינם מספיקים יותר כשמנהלים מספר פרויקטים מורכבים בו-זמנית. פתרונות ענן לאומדן מאפשרים גישה בכל מקום, שיתוף פעולה בזמן אמת ועדכון מחירים אוטומטי. פלטפורמת ConWize לאומדן ותמחור מייצגת את הדור הבא של כלים אלה: ממשק עברי, כתב כמויות מובנה, ניהול מכרזים ושליטה בתקציב – הכל מקום אחד.
חיסכון ממוצע בזמן אומדן: 35–50%
ירידה בשגיאות תמחור: עד 70%
זמינות מהשטח: עדכון ומעקב ישירות מהסמארטפון
טכנולוגיה 3: פלטפורמות ניהול פרויקטים בענן
כלים כמו Procore, PlanGrid ומקבילות ישראליות מאפשרות ניהול לוחות זמנים, עבודות וחוזים מרכזי – עם ניראות מלאה לכל בעלי העניין בפרויקט. לפי Dodge Data & Analytics, חברות שמשתמשות בפלטפורמות ניהול פרויקטים מדווחות על עמידה בלוחות זמנים גבוהה ב-30% לעומת חברות שאינן משתמשות.
ניהול RFI ותוכניות ישירות מהאפליקציה
תיעוד אוטומטי של כל החלטה ואירוע בשטח
דשבורד סטטוס לכל קבלן ומשימה
טכנולוגיה 4: ניתוח נתוני שטח ו-IoT
חיישנים, מצלמות ומכשירי IoT שמוצבים באתר הבנייה מאפשרים מעקב בזמן אמת אחר התקדמות עבודות, שימוש בציוד ותנאי בטיחות. הנתונים מוזנים לפלטפורמות ניתוח שמאפשרות לזהות עיכובים, בזבוז ומפגעי בטיחות לפני שהם הופכים לבעיות.
ניטור ממשי של שעות עבודה ונוכחות
מעקב GPS אחר ציוד וכלי רכב
התראות בטיחות אוטומטיות
טכנולוגיה 5: בינה מלאכותית לתמחור ואומדן
הדור הבא של כלי האומדן משלב בינה מלאכותית שמנתחת פרויקטים קודמים ומחירי שוק כדי לייצר אומדנים מדויקים יותר. מערכות AI מסוגלות לזהות חריגות, להצביע על סיכוני עלות ולהציע חלופות תכנוניות זולות יותר – כל זאת בשבריר מהזמן שצוות אנושי היה זקוק לו.
לפי סקר Autodesk מ-2024, 68% ממנהלי הפרויקטים בעולם מאמינים ש-AI תהיה מרכזית בתמחור ואומדן תוך שלוש שנים.
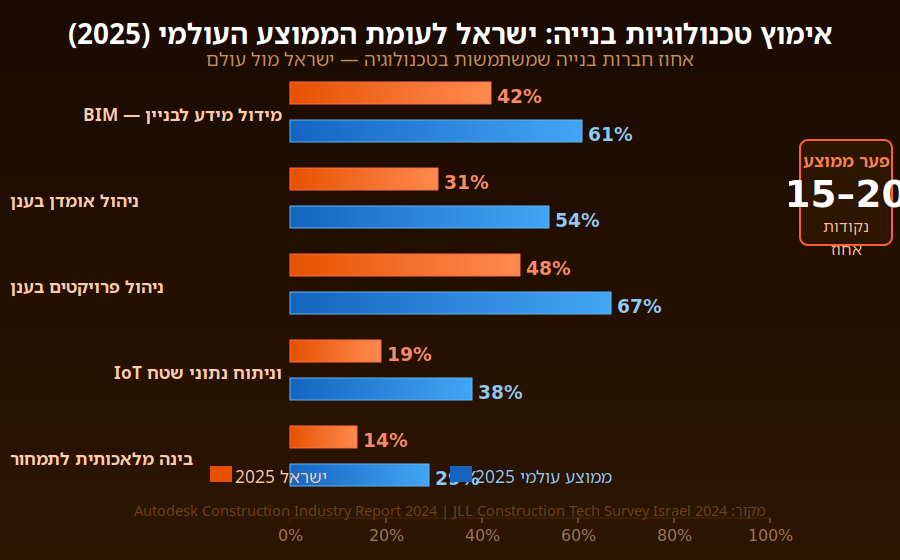
טבלת השוואה: שיעורי אימוץ טכנולוגיות בנייה בישראל (2025)
| טכנולוגיה | שיעור אימוץ (ישראל) | שיעור אימוץ (עולמי) |
| BIM | 42% | 61% |
| ניהול אומדן בענן | 31% | 54% |
| ניהול פרויקטים בענן | 48% | 67% |
| IoT וניתוח שטח | 19% | 38% |
| AI לתמחור ואומדן | 14% | 29% |
מקור: Autodesk Construction Industry Report 2024; JLL Construction Tech Survey Israel 2024
מה שוק הבנייה בישראלי צריך לדעת
ישראל מאמצת טכנולוגיות בנייה בקצב איטי יותר מהממוצע העולמי – אך הפער מצטמצם. הנהגת מחייבת BIM בפרויקטים ציבוריים, עלייה בהיקפי הבנייה ותחרות גוברת על כוח אדם מיומן יוצרים לחץ שמאיץ את קצב האימוץ. חברות שיתחילו את המעבר הדיגיטלי עכשיו ייהנו מיתרון ראשון-מגיע שיהיה קשה לשחזר בעוד שלוש שנים.
התחילו בכלי ה-ROI המהיר ביותר: ניהול אומדן ותמחור דיגיטלי
צרו מסד נתונים פנימי של עלויות מפרויקטים קודמים
השקיעו בהכשרת צוות – הטכנולוגיה טובה בדיוק כמו האנשים שמשתמשים בה
בחרו פלטפורמה עם תמיכה מקומית ותיעוד בעברית
סיכום
הטרנספורמציה הדיגיטלית של שוק הבנייה הישראלי אינה שאלה של ‘אם’ אלא של ‘מתי’. הכלים שפעם היו נחלת חברות הבנייה הגדולות ביותר בעולם הפכו נגישים, מותאמים מקומית ומוכחים בשטח. חברות שישכילו לאמץ טכנולוגיות אלה יוכלו לנהל פרויקטים מורכבים יותר, לשמור על שולי רווח בריאים ולספק ללקוחות שלהן רמת מקצועיות שהמתחרים לא יוכלו להציע. זהו הרגע לפעול
Tomato Breeders and the Push Toward Innovative Specialty Varieties
Cloud Based Live Video Production and the AI Live Production Unit
Book Digitization, Copy Stands, and Digitizing the Autochrome Process

-
 Business Solutions2 years ago
Live Video Broadcasting with Bonded Transmission Technology
-
 Business Solutions1 year ago
The Future of Healthcare SMS and RCS Messaging
-
 Business Solutions2 years ago
2-Way Texting Solutions from Company Message Services
-
 Business Solutions2 years ago
Communication with Analog to Fiber Converters & RF Link Budgets
-
 DSRC Communication1 year ago
The Crossroads of Connectivity: DSRC vs. C-V2X Technologies in Automotive Communication
-
 Business Solutions2 years ago
Wholesale SMS Platforms with OTP Services
-
 3D Technology1 year ago
How Multispectral Cameras Advance Book Scanning
-
 Business Solutions2 years ago
Choosing the Right B2B Digital Marketing Agency: A Guide