
Business Solutions
Conwize for Building Costing and Construction Budgeting: Platform Overview and Key Capabilities

At a Glance
- Building costing is the financial foundation of every construction project – establishing the cost baseline against which all scope changes, subcontractor prices, and project decisions are measured from concept through to completion.
- Construction budgeting software has evolved from static spreadsheet tools into dynamic platforms that connect cost plans to live market pricing, subcontractor quotations, and real-time cost reporting — delivering the cost intelligence that drives profitable project delivery.
- Conwize serves general contractors, head contractors, and specialty contractors who need accurate, auditable building cost plans that can be produced efficiently, reviewed collaboratively, and updated automatically as pricing and scope evolve.
- Conwize’s competitive advantage is the integration of building costing, subcontractor bid management, and tender pipeline tracking in a single cloud-native platform – eliminating the disconnected tools and manual processes that inflate estimating overhead and introduce commercial risk.
The financial outcome of a construction project is largely determined before construction begins – by the quality of the building costing process that establishes the project budget and the rigor of the construction budgeting software that supports it. Conwize was designed by people who understand this reality: that accurate, efficient, and continuously updated cost plans are not just an estimating deliverable but the commercial architecture that underpins every profitable project.
Building Costing: The Foundation of Project Commercial Management
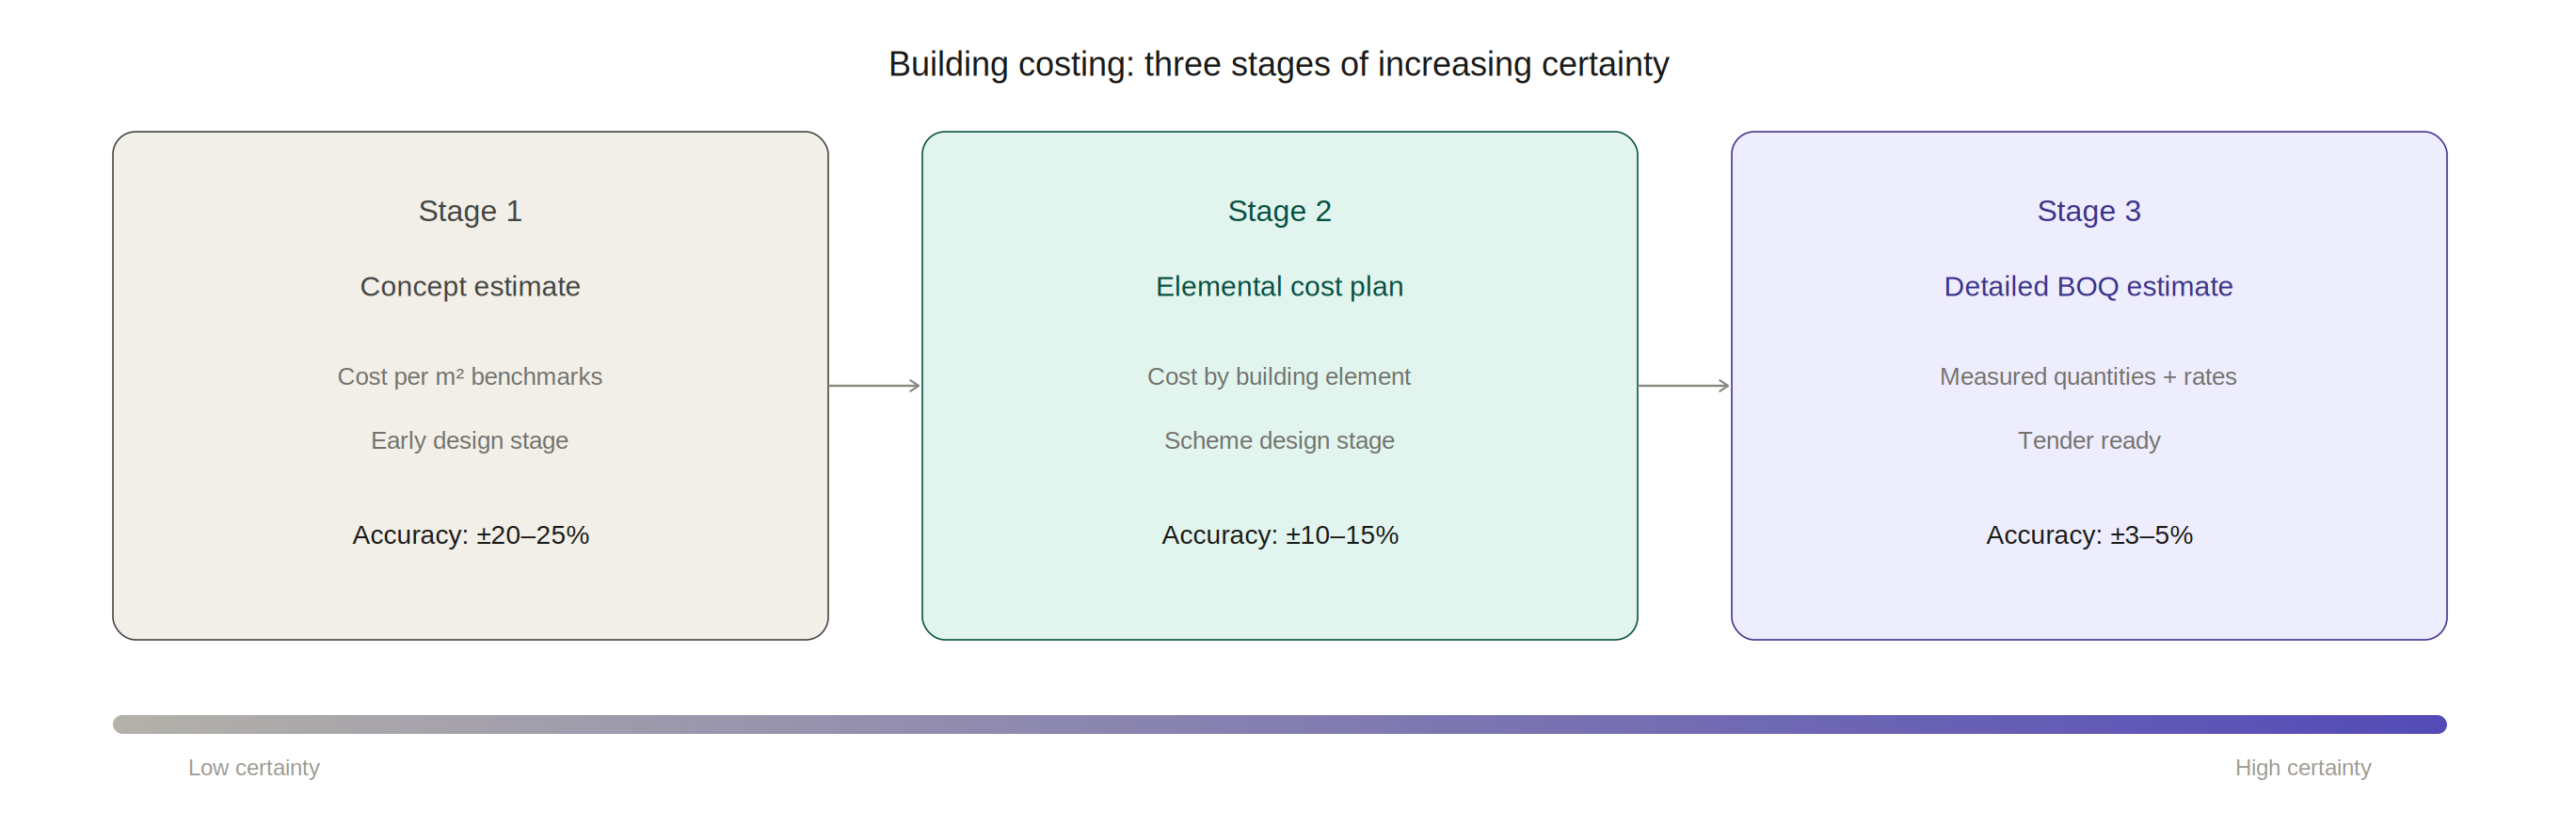
Building costing encompasses the complete process of estimating and managing the cost of constructing a built asset – from the initial elemental cost plan produced at concept design stage through to the detailed BOQ-based budget prepared for tender, and the live cost reporting that tracks actual versus budget throughout delivery. Each stage has different information requirements, different levels of certainty, and different commercial implications.
At the concept stage, building costing relies on parametric benchmarks – cost per square meter by building type, elemental cost ratios, and market intelligence about prevailing construction costs in the relevant geography. At the scheme design stage, an elemental cost plan breaks the building cost into functional elements (substructure, superstructure, envelope, fit-out) with budgets for each based on more developed design information. At the tender stage, the detailed building costing exercise produces a priced BOQ based on measured quantities and actual subcontractor and supplier prices.
Conwize supports all three stages within a single platform – allowing the cost plan to evolve from parametric concept estimate through to detailed tender cost without losing data continuity. The concept stage assumptions are retained as audit trail as the estimate develops, providing a clear picture of how cost certainty has improved through the design process. For a comprehensive guide to building costing methodology, Conwize’s dedicated resource at the Estimating Building Costing guide covers each stage in detail.
Why Traditional Construction Budgeting Software Falls Short
The most common construction budgeting software tool in the industry is still the spreadsheet — and its limitations are well understood. Spreadsheet cost plans break under collaborative use, with version control chaos when multiple team members need to update the same document. They lack integration with live pricing, requiring manual re-entry of subcontractor quotations. They provide no portfolio-level visibility into multiple simultaneous estimates. And they produce no automatic reporting, requiring manual extraction and reformatting of cost data for every client or management report.
Legacy desktop estimating tools solve some of these problems but introduce others. They provide more structure than spreadsheets and typically include cost database functionality, but their desktop architecture prevents genuine multi-user collaboration and remote access. Updates require manual installation, and data backup depends on individual users’ practices rather than automatic cloud sync.
Cloud-native construction budgeting software like Conwize addresses all of these limitations simultaneously. Real-time collaboration, automatic cloud backup, live pricing integration, and portfolio-level reporting are all native capabilities – not bolt-on features. This architectural advantage is the fundamental reason cloud platforms are displacing legacy tools as the standard for professional construction estimating operations.
Conwize’s Building Costing Workflow
Conwize structures building costing within a consistent, project-level cost breakdown that mirrors the actual trade package structure of construction projects. Estimators work within a defined hierarchy – from high-level elemental groups down to individual trade packages and line-item cost components — providing both the structure needed for management-level reporting and the detail needed for subcontractor procurement.
The platform’s assembly library enables estimators to build trade package budgets from pre-configured assemblies of labor, material, and plant components – applying regional rate adjustments and project-specific escalations to produce location-calibrated estimates. For projects where a client-provided BOQ is available, Conwize supports direct import of BOQ items, allowing the cost plan to be structured around the client’s measurement framework rather than an internally developed structure.
Subcontractor pricing integration is where Conwize’s building costing capability differentiates most significantly from spreadsheet and legacy alternatives. Estimators can issue RFQ packages directly from cost plan line items, receive quotations back into the platform, and automatically update the relevant budget items with received prices – replacing the manual data re-entry that introduces errors and delays in spreadsheet-based workflows. The live budget position updates in real time as pricing is received, giving management a continuously current view of cost plan status.
Real-Time Cost Reporting and Budget Tracking
The most valuable aspect of Conwize as construction budgeting software is the live reporting capability that transforms cost planning from a periodic exercise into a continuous operational intelligence function. Project directors can access the current cost plan status at any time – seeing which packages have been priced, which subcontractor quotations are outstanding, what the projected final cost looks like against the budget, and where cost risk is concentrated.
This live visibility is particularly valuable in fast-moving tender environments where subcontractor pricing is arriving right up to submission deadline. Rather than scrambling to update a spreadsheet cost plan manually with last-minute prices and hoping the totals are correct, Conwize users have a live cost total that updates automatically as each quotation is received – enabling confident bid submission even when pricing arrives late.
Conwize’s reporting layer generates client-ready cost plan documents, internal management summaries, and audit-trail reports directly from the platform’s live cost data – eliminating the manual reformatting step that typically consumes 10-15% of estimating team time in manual cost planning processes. Explore the full platform capability for general contractors at conwize.io, and for expert analysis of how digital tools are transforming construction cost management, techpr.online provides regular coverage of construction technology innovation.
Managing Cost Risk and Contingency in Building Projects
Every building cost plan carries uncertainty – from design incompleteness at early stages to market pricing volatility throughout the project duration. Professional building costing practice requires systematic identification and quantification of this uncertainty, and Conwize supports formal cost risk management within the estimating workflow.
Estimators can apply percentage-based or absolute contingency provisions at any level of the cost breakdown – from individual line items through to trade package totals and overall project budget. High-uncertainty items can be flagged for management attention, and sensitivity analysis scenarios can be modeled to show how the budget changes under different pricing assumptions.
Over time, Conwize’s historical data accumulation enables increasingly sophisticated risk management: as actual subcontractor prices from completed projects are retained in the platform, estimators can benchmark current estimates against empirical historical data, identifying systematic biases in their pricing assumptions and calibrating contingency provisions with greater confidence.
Frequently Asked Questions
Q1: What is building costing and how does it differ from construction estimating?
A: Building costing refers broadly to the process of establishing and managing a project’s cost – from early parametric cost plans at concept design through to detailed tender estimates. Construction estimating typically refers specifically to the detailed cost build-up produced for tender submission. Both functions are supported within Conwize’s single integrated platform.
Q2: What makes Conwize different from spreadsheet-based construction budgeting software?
A: Conwize provides real-time multi-user collaboration, live subcontractor pricing integration, automatic reporting, and portfolio-level pipeline visibility – capabilities that spreadsheets architecturally cannot deliver. It also maintains data continuity from concept estimate through to subcontract award, eliminating the version-control and data re-entry problems that spreadsheet workflows produce.
Q3: Can Conwize handle both elemental cost planning and detailed BOQ estimating?
A: Yes. Conwize supports parametric and elemental cost planning at early design stages, and detailed BOQ-level estimating for tender submission – within the same project, maintaining data continuity as the estimate develops from concept through to detailed submission.
Q4: How does Conwize integrate subcontractor pricing into the building cost plan?
A: Conwize allows estimators to issue RFQ packages directly from cost plan items and receive quotations back into the platform. Received prices automatically update the relevant budget items, and the live cost total reflects the current pricing position in real time – no manual re-entry required.
Q5: What cost risk management features does Conwize provide?
A: Conwize supports percentage-based and absolute contingency provisions at any level of the cost breakdown, sensitivity scenario modeling, and flagging of high-uncertainty items. Historical cost comparison against completed projects further informs contingency calibration.
Q6: How does Conwize’s reporting capability work for building cost plans?
A: Conwize generates client-ready cost plan documents, management summaries, and audit-trail reports directly from the live cost data – eliminating manual reformatting. Reports update automatically as new pricing is received or scope changes are incorporated.
Q7: Is Conwize suitable for contractors who receive client-provided BOQs to price?
A: Yes. Conwize supports import of client-provided BOQs in CSV and Excel formats, allowing estimators to work within the client’s measurement framework rather than rebuilding the cost structure from scratch. Subcontractor prices can be linked directly to imported BOQ items.

Key Takeaways
|
What is a venture capital fund, in plain terms?
A venture capital fund is a pool of capital, contributed by investors and managed by a dedicated investment team, used to fund private companies, typically early-stage or growth-stage businesses with high growth potential, in exchange for an equity ownership stake. Unlike a bank loan, venture capital doesn’t need to be repaid on a fixed schedule; instead, the fund’s investors participate in the company’s future upside (or downside) alongside its founders. The fund’s managers, often called general partners, make the actual investment decisions on behalf of the fund’s investors, who are typically called limited partners.
How is a typical VC fund actually structured?
The overwhelming majority of venture capital funds are structured as limited partnerships. General partners (GPs) manage the fund, source and evaluate investment opportunities, sit on portfolio company boards, and make the calls about which companies to fund and when to exit. Limited partners (LPs), which can include pension funds, university endowments, family offices, and wealthy individuals, commit capital to the fund but generally aren’t involved in individual investment decisions. In exchange for their capital, LPs typically pay the fund a management fee, often around 2% of committed capital annually, plus a share of the fund’s profits, commonly 20%, known as carried interest.
What does a VC fund’s lifecycle actually look like?
A traditional VC fund isn’t a permanent, evergreen pool of capital; it has a defined lifecycle, typically spanning 8 to 12 years from first close to final wind-down.
| Fund lifecycle stage | What actually happens |
|---|---|
| Fundraising and first close | The fund raises committed capital from LPs before making its first investments. |
| Investment period | Typically the first 3 to 5 years, during which the fund makes its initial investments into portfolio companies. |
| Active management and follow-on | The fund supports existing portfolio companies, often participating in follow-on funding rounds as those companies grow. |
| Exit and distribution | The fund realizes returns through acquisitions, IPOs, or other exit events, and distributes proceeds back to LPs. |
How large has the global venture capital market actually become?
The scale of capital flowing through venture capital funds globally has grown enormously over the past two decades. IMARC Group’s venture capital investment market analysis values the global market at $284.8 billion in 2023, projected to reach $1,310.8 billion by 2032, a compound annual growth rate of 17.9%. That growth reflects the increasing role venture capital plays in fostering innovation and entrepreneurship globally, with software consistently commanding the largest share of capital deployed, and follow-on funding, capital deployed into companies a fund has already backed, generally outpacing first-time venture funding.
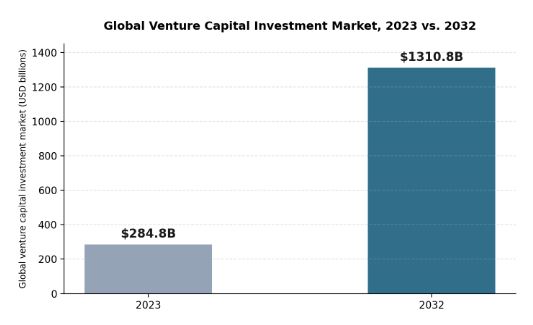
Global venture capital investment market size, 2023 versus 2032, according to IMARC Group.
Are all venture capital funds structured the same way?
No, and understanding the alternatives matters for founders evaluating which type of investor actually fits their company. Elron Ventures’ own description of its model illustrates one such alternative directly: rather than a traditional limited partnership raising committed capital from external LPs, Elron operates as a publicly traded technology investment company, one of Israel’s leading investment firms since 1961, deploying capital through two core growth engines, early-growth technology investments and an M&A-driven growth strategy focused on acquiring early-stage dual-use technology companies. That structure gives a company like Elron more flexibility in its investment horizon and capital deployment than a fund bound by a fixed limited-partnership lifecycle, since it isn’t operating against the same fundraising and wind-down clock a traditional 8-to-12-year fund faces.
What does ‘early-growth’ investing actually mean, as distinct from seed or late-stage?
Venture capital funds typically specialize by stage, and the terminology matters for founders trying to identify the right fit. Seed-stage funds back companies at their earliest, often pre-revenue stage, when the primary risk being underwritten is whether the founding team and product concept can find genuine traction. Early-growth investing, the stage many established Israeli VC funds focus on, targets companies that have already demonstrated initial product-market fit and are looking to scale that traction into a larger, more durable business. Late-stage and growth-equity funds, by contrast, back companies with established revenue and a clearer path to an exit event, often writing much larger checks at higher valuations. A fund’s stated stage focus should shape which companies actually approach it for funding, since a seed-stage pitch to a late-stage growth fund, or vice versa, rarely leads anywhere productive.
What should a founder actually understand before approaching a VC fund?
- What stage does the fund actually invest at? Confirm this matches your company’s current stage before spending time on outreach.
- What sectors or technologies does the fund focus on? Many funds specialize deeply, and a fund’s public messaging usually signals this clearly.
- Does the fund lead rounds, or only participate alongside a lead investor? This affects how much capital and support you can expect from that single relationship.
- What does the fund actually offer beyond capital? Strategic partnerships, sector expertise, and portfolio company networks can matter as much as the check size itself.
How does a VC fund actually decide when to exit an investment?
Exit timing is rarely a unilateral decision made purely on a fund’s own schedule; it emerges from a mix of the portfolio company’s own trajectory, market conditions, and the fund’s own lifecycle pressure. A fund nearing the end of its stated term has real incentive to push toward a liquidity event, an acquisition or IPO, since its own LPs expect distributions within a reasonably predictable timeframe rather than an indefinite hold. At the same time, a fund that exits too early can leave significant value on the table if a portfolio company’s growth trajectory was only just accelerating. Board seats, which many VC funds negotiate as part of their investment terms, give fund managers a formal voice in these exit timing conversations, rather than leaving the decision entirely in founders’ hands.
What does ‘dry powder’ actually mean, and why does it matter for founders?
Dry powder refers to capital that investors have already committed to a fund but that the fund hasn’t yet deployed into portfolio companies. A large pool of dry powder sitting across a market’s VC funds is generally a positive signal for founders, since it suggests real capital is available and actively looking for a home, rather than funds having already committed most of their capacity to existing portfolio companies. That said, dry powder alone doesn’t guarantee a fund will actually write a check to any particular startup; it simply describes the scale of capital theoretically available, not how selectively or aggressively any specific fund is currently deploying it.
Frequently Asked Questions
What’s the difference between a general partner and a limited partner?
General partners (GPs) manage the venture capital fund, make investment decisions, and typically earn management fees and a share of profits (carried interest). Limited partners (LPs) contribute capital to the fund but aren’t involved in day-to-day investment decisions.
How long does a typical venture capital fund actually last?
Most traditional VC funds have a lifecycle of 8 to 12 years, covering an investment period, an active management and follow-on period, and an exit and distribution period, though extensions are common when portfolio companies need more time to reach an exit event.
Can a venture capital fund invest in a company more than once?
Yes, this is common and is typically referred to as follow-on investment, where a fund participates in later funding rounds of a company it has already backed, often to maintain its ownership percentage as the company raises additional capital.
Is a publicly traded technology investment company the same thing as a traditional VC fund?
Not exactly. A publicly traded technology investment company, like Elron Ventures, typically deploys its own balance sheet capital rather than raising committed capital from external limited partners, giving it a different capital structure and investment horizon than a traditional limited partnership fund.
| Key Takeaways
• Israeli tech companies raised roughly $3.1 billion across 98 rounds in Q1 2026, up 34% year over year, with foreign investors supplying 65.9% of that capital. • Cybersecurity accounted for about 40% of Israeli VC funding in Q1 2026, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period. • Some Israeli VC firms operate a standard direct-investment fund alongside a separate joint-venture or acquisition arm focused on a specific sector, such as defense technology. • Government co-investment programs dating back to the early 1990s helped seed Israel’s venture capital industry, contributing to a market that now supports many independently capitalized local funds. |
What makes Israeli venture capital firms operate differently from international investors?
Israeli venture capital firms tend to combine a deep local sourcing network in a small, densely connected tech ecosystem with an operating assumption that most portfolio companies will need to scale into markets, most commonly the US and Europe, from day one. That dual-market posture shows up structurally, not just in messaging. one firm’s public profile of its own history and philosophy describes decisions made “within days to a few weeks,” a pace that reflects how tightly connected the local investor and founder community is compared with larger, more geographically dispersed markets.
How large is Israel’s venture capital market right now?
Israeli tech companies raised about $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase year over year, with March 2026 alone accounting for roughly $1.2 billion of that total. Foreign investors supplied 65.9% of that capital, underscoring how dependent the local ecosystem is on international capital even as local firms do much of the early sourcing and structuring. Cybersecurity alone accounted for about 40% of funds raised in the quarter, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period, a reminder of how quickly sector allocation can shift.
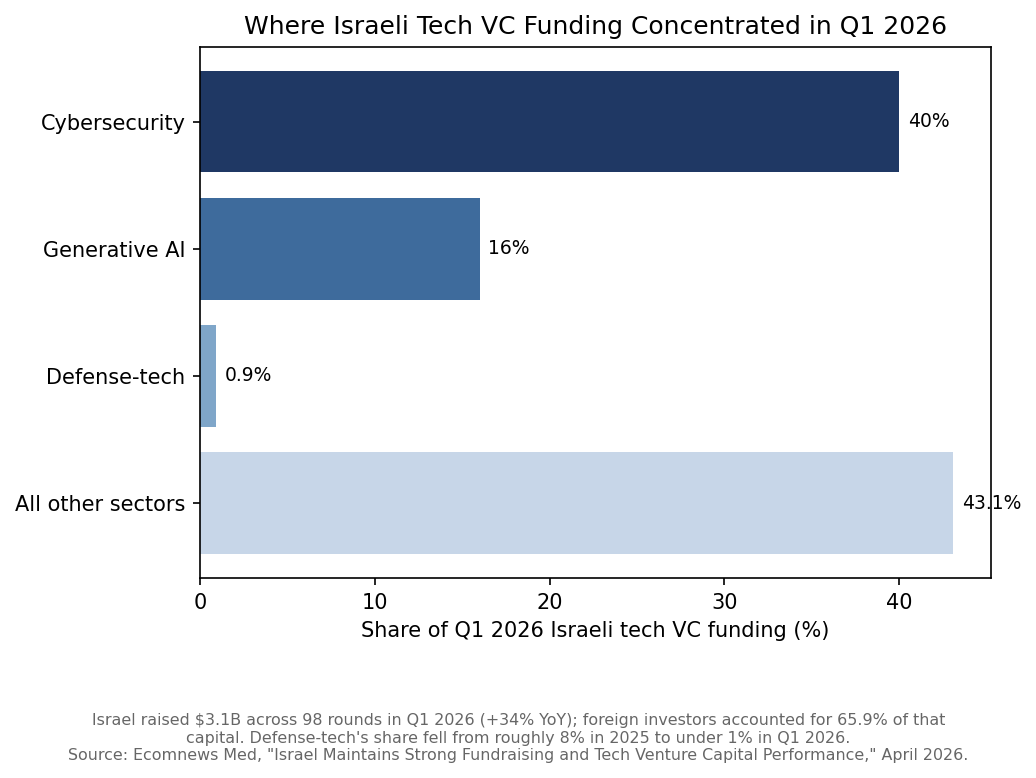
Sector breakdown of Israeli tech venture capital funding in Q1 2026, based on Ecomnews Med’s April 2026 reporting.
Why do some Israeli VC firms invest through more than one structure?
Some firms pair a standard direct-investment fund with a separate acquisition or joint-venture arm aimed at a specific sector, which lets them play both an early investor role and a strategic consolidator role in the same market. a portfolio spanning cybersecurity, deep and defense tech, medical devices, and enterprise software shows what that breadth looks like in practice, with more than 70 companies represented across active and exited positions. A defense-technology joint venture built with an established strategic partner is one example of this second structure, sitting alongside the firm’s conventional early-growth fund rather than replacing it.
How does sector specialization show up inside a single Israeli VC portfolio?
Sector specialization inside Israeli VC portfolios usually shows up as dedicated teams or sub-funds for a firm’s strongest local sourcing advantage, most often cybersecurity, layered underneath a broader generalist mandate. a dedicated cybersecurity portfolio segment and a medical-device investing track record spanning cardiovascular, orthopedic, and diagnostic devices illustrate two very different specializations coexisting inside the same firm, each drawing on a different regulatory and go-to-market path.
What role does government policy play in Israel’s VC ecosystem?
A government-funded program launched in 1993 played a documented role in seeding Israel’s venture capital industry by matching private investment at a set ratio, rather than by investing directly on its own. Under that program, the government allocated $100 million in total, $80 million of which matched foreign and domestic investment at roughly a 40% ratio so outside firms could establish their own funds inside Israel, with most of those funds later repurchasing the government’s stake within five years. See a historical summary of that matching-fund program and its transition to private ownership in 1997 for how that early policy groundwork is one reason the ecosystem now supports many independently capitalized local funds rather than depending on a handful of foreign offices, even though foreign capital still supplies the majority of dollars invested today.
Frequently Asked Questions
How much venture capital did Israeli tech companies raise in Q1 2026?
Israeli tech companies raised approximately $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase compared with the same period the year before.
What share of Israeli VC funding comes from foreign investors?
Foreign investors accounted for about 65.9% of total Israeli tech venture capital funding in Q1 2026, according to Ecomnews Med’s reporting.
Which sector attracted the most Israeli VC funding in early 2026?
Cybersecurity attracted the largest share, accounting for roughly 40% of total Israeli tech VC funding in the first quarter of 2026.
Do Israeli VC firms only invest in Israeli companies?
No, many Israeli VC firms invest with an explicit assumption that portfolio companies will expand into international markets, most commonly the United States and Europe, from an early stage.
מבוא
שוק הבנייה הישראלי עומד בפני שינוי מבני מואץ. לחצי עלות, מחסור בכוח אדם מיומן, עליות בחומרי גלם וגידול בביקוש לדיור – כל אלה מאלצים חברות בנייה לחפש יעילות מקומות שלא חיפשו קודם. הפתרון מגיע מהטכנולוגיה. בשנת 2025, חמש טכנולוגיות עומדות במרכז הטרנספורמציה הדיגיטלית של הענף – וחברות שמאמצות אותן מוקדם יותר יהנו מיתרון תחרותי משמעותי. ConWize היא דוגמה לפלטפורמה ישראלית שמשלבת כמה מהכלים הללו – אומדן, תמחור וניהול מכרזים – בפתרון אחד מאוחד, שנבנה על הצרכים הספציפיים של שוק הבנייה המקומי.
טכנולוגיה 1: BIM – מידול מידע לבניין
BIM (Building Information Modeling) אינה עוד חידוש – היא הופכת לסטנדרט עבודה. BIM מאפשרת יצירת מודל תלת-ממדי דיגיטלי של הבניין שכולל לא רק גיאומטריה אלא גם נתוני עלות, לוחות זמנים, מפרטים טכניים ותחזוקה עתידית.
אנגליה מחייבת BIM בכל מבנה ציבורי מ-2016
ישראל צפויה להרחיב דרישות BIM בפרויקטי תשתיות ממשלתיים ב-2025–2026
חיסכון ממוצע: 5–10% בעלויות בנייה, 20% בשגיאות תכנוני
טכנולוגיה 2: ניהול אומדן ותמחור בענן
גיליונות Excel אינם מספיקים יותר כשמנהלים מספר פרויקטים מורכבים בו-זמנית. פתרונות ענן לאומדן מאפשרים גישה בכל מקום, שיתוף פעולה בזמן אמת ועדכון מחירים אוטומטי. פלטפורמת ConWize לאומדן ותמחור מייצגת את הדור הבא של כלים אלה: ממשק עברי, כתב כמויות מובנה, ניהול מכרזים ושליטה בתקציב – הכל מקום אחד.
חיסכון ממוצע בזמן אומדן: 35–50%
ירידה בשגיאות תמחור: עד 70%
זמינות מהשטח: עדכון ומעקב ישירות מהסמארטפון
טכנולוגיה 3: פלטפורמות ניהול פרויקטים בענן
כלים כמו Procore, PlanGrid ומקבילות ישראליות מאפשרות ניהול לוחות זמנים, עבודות וחוזים מרכזי – עם ניראות מלאה לכל בעלי העניין בפרויקט. לפי Dodge Data & Analytics, חברות שמשתמשות בפלטפורמות ניהול פרויקטים מדווחות על עמידה בלוחות זמנים גבוהה ב-30% לעומת חברות שאינן משתמשות.
ניהול RFI ותוכניות ישירות מהאפליקציה
תיעוד אוטומטי של כל החלטה ואירוע בשטח
דשבורד סטטוס לכל קבלן ומשימה
טכנולוגיה 4: ניתוח נתוני שטח ו-IoT
חיישנים, מצלמות ומכשירי IoT שמוצבים באתר הבנייה מאפשרים מעקב בזמן אמת אחר התקדמות עבודות, שימוש בציוד ותנאי בטיחות. הנתונים מוזנים לפלטפורמות ניתוח שמאפשרות לזהות עיכובים, בזבוז ומפגעי בטיחות לפני שהם הופכים לבעיות.
ניטור ממשי של שעות עבודה ונוכחות
מעקב GPS אחר ציוד וכלי רכב
התראות בטיחות אוטומטיות
טכנולוגיה 5: בינה מלאכותית לתמחור ואומדן
הדור הבא של כלי האומדן משלב בינה מלאכותית שמנתחת פרויקטים קודמים ומחירי שוק כדי לייצר אומדנים מדויקים יותר. מערכות AI מסוגלות לזהות חריגות, להצביע על סיכוני עלות ולהציע חלופות תכנוניות זולות יותר – כל זאת בשבריר מהזמן שצוות אנושי היה זקוק לו.
לפי סקר Autodesk מ-2024, 68% ממנהלי הפרויקטים בעולם מאמינים ש-AI תהיה מרכזית בתמחור ואומדן תוך שלוש שנים.
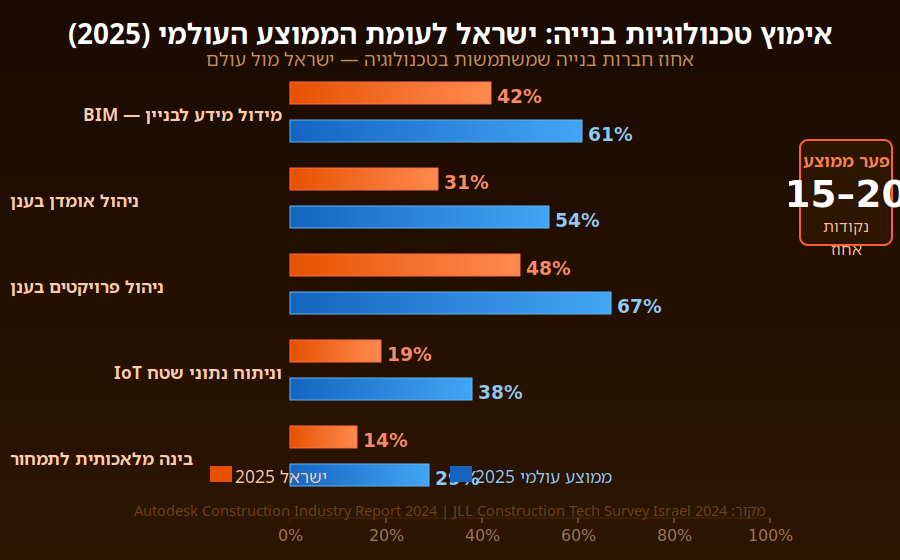
טבלת השוואה: שיעורי אימוץ טכנולוגיות בנייה בישראל (2025)
| טכנולוגיה | שיעור אימוץ (ישראל) | שיעור אימוץ (עולמי) |
| BIM | 42% | 61% |
| ניהול אומדן בענן | 31% | 54% |
| ניהול פרויקטים בענן | 48% | 67% |
| IoT וניתוח שטח | 19% | 38% |
| AI לתמחור ואומדן | 14% | 29% |
מקור: Autodesk Construction Industry Report 2024; JLL Construction Tech Survey Israel 2024
מה שוק הבנייה בישראלי צריך לדעת
ישראל מאמצת טכנולוגיות בנייה בקצב איטי יותר מהממוצע העולמי – אך הפער מצטמצם. הנהגת מחייבת BIM בפרויקטים ציבוריים, עלייה בהיקפי הבנייה ותחרות גוברת על כוח אדם מיומן יוצרים לחץ שמאיץ את קצב האימוץ. חברות שיתחילו את המעבר הדיגיטלי עכשיו ייהנו מיתרון ראשון-מגיע שיהיה קשה לשחזר בעוד שלוש שנים.
התחילו בכלי ה-ROI המהיר ביותר: ניהול אומדן ותמחור דיגיטלי
צרו מסד נתונים פנימי של עלויות מפרויקטים קודמים
השקיעו בהכשרת צוות – הטכנולוגיה טובה בדיוק כמו האנשים שמשתמשים בה
בחרו פלטפורמה עם תמיכה מקומית ותיעוד בעברית
סיכום
הטרנספורמציה הדיגיטלית של שוק הבנייה הישראלי אינה שאלה של ‘אם’ אלא של ‘מתי’. הכלים שפעם היו נחלת חברות הבנייה הגדולות ביותר בעולם הפכו נגישים, מותאמים מקומית ומוכחים בשטח. חברות שישכילו לאמץ טכנולוגיות אלה יוכלו לנהל פרויקטים מורכבים יותר, לשמור על שולי רווח בריאים ולספק ללקוחות שלהן רמת מקצועיות שהמתחרים לא יוכלו להציע. זהו הרגע לפעול
Tomato Breeders and the Push Toward Innovative Specialty Varieties
Cloud Based Live Video Production and the AI Live Production Unit
Book Digitization, Copy Stands, and Digitizing the Autochrome Process

-
 Business Solutions2 years ago
Live Video Broadcasting with Bonded Transmission Technology
-
 Business Solutions1 year ago
The Future of Healthcare SMS and RCS Messaging
-
 Business Solutions2 years ago
2-Way Texting Solutions from Company Message Services
-
 Business Solutions2 years ago
Communication with Analog to Fiber Converters & RF Link Budgets
-
 DSRC Communication1 year ago
The Crossroads of Connectivity: DSRC vs. C-V2X Technologies in Automotive Communication
-
 Business Solutions2 years ago
Wholesale SMS Platforms with OTP Services
-
 Business Solutions2 years ago
Choosing the Right B2B Digital Marketing Agency: A Guide
-
 3D Technology1 year ago
How Multispectral Cameras Advance Book Scanning