
Business Solutions
What Is a Venture Capital Fund? How VC Funds Actually Work

Key Takeaways
|
What is a venture capital fund, in plain terms?
A venture capital fund is a pool of capital, contributed by investors and managed by a dedicated investment team, used to fund private companies, typically early-stage or growth-stage businesses with high growth potential, in exchange for an equity ownership stake. Unlike a bank loan, venture capital doesn’t need to be repaid on a fixed schedule; instead, the fund’s investors participate in the company’s future upside (or downside) alongside its founders. The fund’s managers, often called general partners, make the actual investment decisions on behalf of the fund’s investors, who are typically called limited partners.
How is a typical VC fund actually structured?
The overwhelming majority of venture capital funds are structured as limited partnerships. General partners (GPs) manage the fund, source and evaluate investment opportunities, sit on portfolio company boards, and make the calls about which companies to fund and when to exit. Limited partners (LPs), which can include pension funds, university endowments, family offices, and wealthy individuals, commit capital to the fund but generally aren’t involved in individual investment decisions. In exchange for their capital, LPs typically pay the fund a management fee, often around 2% of committed capital annually, plus a share of the fund’s profits, commonly 20%, known as carried interest.
What does a VC fund’s lifecycle actually look like?
A traditional VC fund isn’t a permanent, evergreen pool of capital; it has a defined lifecycle, typically spanning 8 to 12 years from first close to final wind-down.
| Fund lifecycle stage | What actually happens |
|---|---|
| Fundraising and first close | The fund raises committed capital from LPs before making its first investments. |
| Investment period | Typically the first 3 to 5 years, during which the fund makes its initial investments into portfolio companies. |
| Active management and follow-on | The fund supports existing portfolio companies, often participating in follow-on funding rounds as those companies grow. |
| Exit and distribution | The fund realizes returns through acquisitions, IPOs, or other exit events, and distributes proceeds back to LPs. |
How large has the global venture capital market actually become?
The scale of capital flowing through venture capital funds globally has grown enormously over the past two decades. IMARC Group’s venture capital investment market analysis values the global market at $284.8 billion in 2023, projected to reach $1,310.8 billion by 2032, a compound annual growth rate of 17.9%. That growth reflects the increasing role venture capital plays in fostering innovation and entrepreneurship globally, with software consistently commanding the largest share of capital deployed, and follow-on funding, capital deployed into companies a fund has already backed, generally outpacing first-time venture funding.
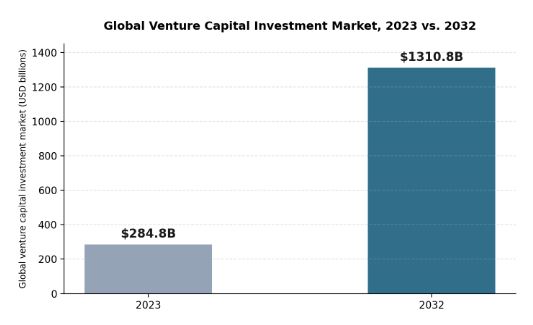
Global venture capital investment market size, 2023 versus 2032, according to IMARC Group.
Are all venture capital funds structured the same way?
No, and understanding the alternatives matters for founders evaluating which type of investor actually fits their company. Elron Ventures’ own description of its model illustrates one such alternative directly: rather than a traditional limited partnership raising committed capital from external LPs, Elron operates as a publicly traded technology investment company, one of Israel’s leading investment firms since 1961, deploying capital through two core growth engines, early-growth technology investments and an M&A-driven growth strategy focused on acquiring early-stage dual-use technology companies. That structure gives a company like Elron more flexibility in its investment horizon and capital deployment than a fund bound by a fixed limited-partnership lifecycle, since it isn’t operating against the same fundraising and wind-down clock a traditional 8-to-12-year fund faces.
What does ‘early-growth’ investing actually mean, as distinct from seed or late-stage?
Venture capital funds typically specialize by stage, and the terminology matters for founders trying to identify the right fit. Seed-stage funds back companies at their earliest, often pre-revenue stage, when the primary risk being underwritten is whether the founding team and product concept can find genuine traction. Early-growth investing, the stage many established Israeli VC funds focus on, targets companies that have already demonstrated initial product-market fit and are looking to scale that traction into a larger, more durable business. Late-stage and growth-equity funds, by contrast, back companies with established revenue and a clearer path to an exit event, often writing much larger checks at higher valuations. A fund’s stated stage focus should shape which companies actually approach it for funding, since a seed-stage pitch to a late-stage growth fund, or vice versa, rarely leads anywhere productive.
What should a founder actually understand before approaching a VC fund?
- What stage does the fund actually invest at? Confirm this matches your company’s current stage before spending time on outreach.
- What sectors or technologies does the fund focus on? Many funds specialize deeply, and a fund’s public messaging usually signals this clearly.
- Does the fund lead rounds, or only participate alongside a lead investor? This affects how much capital and support you can expect from that single relationship.
- What does the fund actually offer beyond capital? Strategic partnerships, sector expertise, and portfolio company networks can matter as much as the check size itself.
How does a VC fund actually decide when to exit an investment?
Exit timing is rarely a unilateral decision made purely on a fund’s own schedule; it emerges from a mix of the portfolio company’s own trajectory, market conditions, and the fund’s own lifecycle pressure. A fund nearing the end of its stated term has real incentive to push toward a liquidity event, an acquisition or IPO, since its own LPs expect distributions within a reasonably predictable timeframe rather than an indefinite hold. At the same time, a fund that exits too early can leave significant value on the table if a portfolio company’s growth trajectory was only just accelerating. Board seats, which many VC funds negotiate as part of their investment terms, give fund managers a formal voice in these exit timing conversations, rather than leaving the decision entirely in founders’ hands.
What does ‘dry powder’ actually mean, and why does it matter for founders?
Dry powder refers to capital that investors have already committed to a fund but that the fund hasn’t yet deployed into portfolio companies. A large pool of dry powder sitting across a market’s VC funds is generally a positive signal for founders, since it suggests real capital is available and actively looking for a home, rather than funds having already committed most of their capacity to existing portfolio companies. That said, dry powder alone doesn’t guarantee a fund will actually write a check to any particular startup; it simply describes the scale of capital theoretically available, not how selectively or aggressively any specific fund is currently deploying it.
Frequently Asked Questions
What’s the difference between a general partner and a limited partner?
General partners (GPs) manage the venture capital fund, make investment decisions, and typically earn management fees and a share of profits (carried interest). Limited partners (LPs) contribute capital to the fund but aren’t involved in day-to-day investment decisions.
How long does a typical venture capital fund actually last?
Most traditional VC funds have a lifecycle of 8 to 12 years, covering an investment period, an active management and follow-on period, and an exit and distribution period, though extensions are common when portfolio companies need more time to reach an exit event.
Can a venture capital fund invest in a company more than once?
Yes, this is common and is typically referred to as follow-on investment, where a fund participates in later funding rounds of a company it has already backed, often to maintain its ownership percentage as the company raises additional capital.
Is a publicly traded technology investment company the same thing as a traditional VC fund?
Not exactly. A publicly traded technology investment company, like Elron Ventures, typically deploys its own balance sheet capital rather than raising committed capital from external limited partners, giving it a different capital structure and investment horizon than a traditional limited partnership fund.

| Key Takeaways
• Israeli tech companies raised roughly $3.1 billion across 98 rounds in Q1 2026, up 34% year over year, with foreign investors supplying 65.9% of that capital. • Cybersecurity accounted for about 40% of Israeli VC funding in Q1 2026, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period. • Some Israeli VC firms operate a standard direct-investment fund alongside a separate joint-venture or acquisition arm focused on a specific sector, such as defense technology. • Government co-investment programs dating back to the early 1990s helped seed Israel’s venture capital industry, contributing to a market that now supports many independently capitalized local funds. |
What makes Israeli venture capital firms operate differently from international investors?
Israeli venture capital firms tend to combine a deep local sourcing network in a small, densely connected tech ecosystem with an operating assumption that most portfolio companies will need to scale into markets, most commonly the US and Europe, from day one. That dual-market posture shows up structurally, not just in messaging. one firm’s public profile of its own history and philosophy describes decisions made “within days to a few weeks,” a pace that reflects how tightly connected the local investor and founder community is compared with larger, more geographically dispersed markets.
How large is Israel’s venture capital market right now?
Israeli tech companies raised about $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase year over year, with March 2026 alone accounting for roughly $1.2 billion of that total. Foreign investors supplied 65.9% of that capital, underscoring how dependent the local ecosystem is on international capital even as local firms do much of the early sourcing and structuring. Cybersecurity alone accounted for about 40% of funds raised in the quarter, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period, a reminder of how quickly sector allocation can shift.
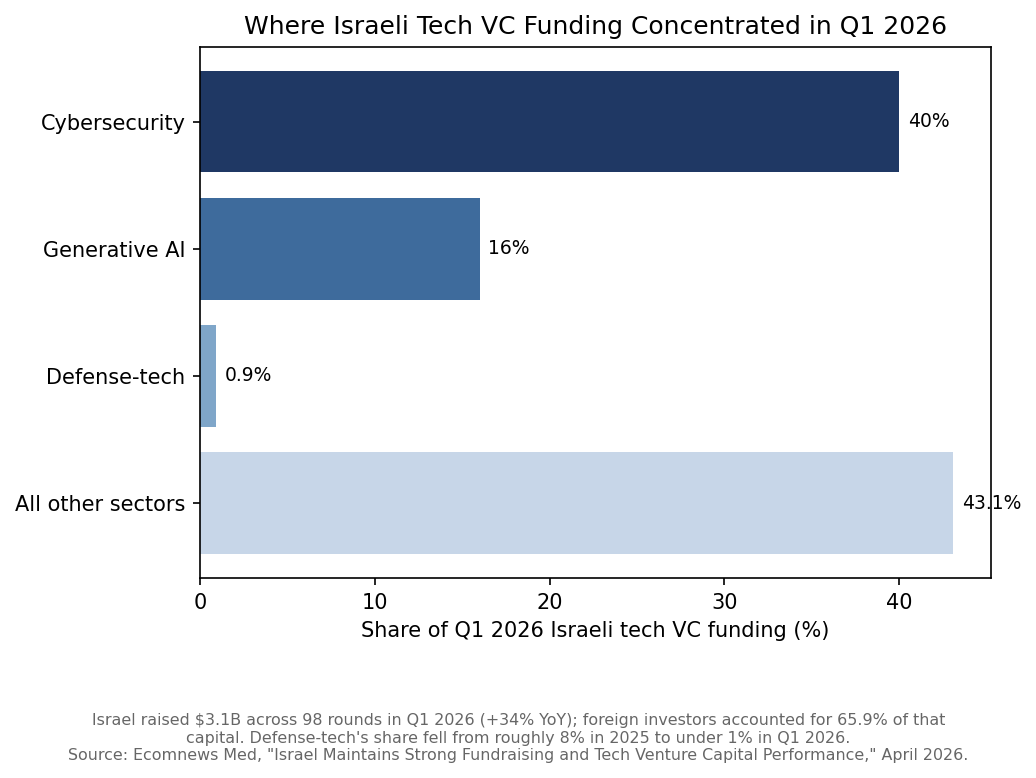
Sector breakdown of Israeli tech venture capital funding in Q1 2026, based on Ecomnews Med’s April 2026 reporting.
Why do some Israeli VC firms invest through more than one structure?
Some firms pair a standard direct-investment fund with a separate acquisition or joint-venture arm aimed at a specific sector, which lets them play both an early investor role and a strategic consolidator role in the same market. a portfolio spanning cybersecurity, deep and defense tech, medical devices, and enterprise software shows what that breadth looks like in practice, with more than 70 companies represented across active and exited positions. A defense-technology joint venture built with an established strategic partner is one example of this second structure, sitting alongside the firm’s conventional early-growth fund rather than replacing it.
How does sector specialization show up inside a single Israeli VC portfolio?
Sector specialization inside Israeli VC portfolios usually shows up as dedicated teams or sub-funds for a firm’s strongest local sourcing advantage, most often cybersecurity, layered underneath a broader generalist mandate. a dedicated cybersecurity portfolio segment and a medical-device investing track record spanning cardiovascular, orthopedic, and diagnostic devices illustrate two very different specializations coexisting inside the same firm, each drawing on a different regulatory and go-to-market path.
What role does government policy play in Israel’s VC ecosystem?
A government-funded program launched in 1993 played a documented role in seeding Israel’s venture capital industry by matching private investment at a set ratio, rather than by investing directly on its own. Under that program, the government allocated $100 million in total, $80 million of which matched foreign and domestic investment at roughly a 40% ratio so outside firms could establish their own funds inside Israel, with most of those funds later repurchasing the government’s stake within five years. See a historical summary of that matching-fund program and its transition to private ownership in 1997 for how that early policy groundwork is one reason the ecosystem now supports many independently capitalized local funds rather than depending on a handful of foreign offices, even though foreign capital still supplies the majority of dollars invested today.
Frequently Asked Questions
How much venture capital did Israeli tech companies raise in Q1 2026?
Israeli tech companies raised approximately $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase compared with the same period the year before.
What share of Israeli VC funding comes from foreign investors?
Foreign investors accounted for about 65.9% of total Israeli tech venture capital funding in Q1 2026, according to Ecomnews Med’s reporting.
Which sector attracted the most Israeli VC funding in early 2026?
Cybersecurity attracted the largest share, accounting for roughly 40% of total Israeli tech VC funding in the first quarter of 2026.
Do Israeli VC firms only invest in Israeli companies?
No, many Israeli VC firms invest with an explicit assumption that portfolio companies will expand into international markets, most commonly the United States and Europe, from an early stage.
מבוא
שוק הבנייה הישראלי עומד בפני שינוי מבני מואץ. לחצי עלות, מחסור בכוח אדם מיומן, עליות בחומרי גלם וגידול בביקוש לדיור – כל אלה מאלצים חברות בנייה לחפש יעילות מקומות שלא חיפשו קודם. הפתרון מגיע מהטכנולוגיה. בשנת 2025, חמש טכנולוגיות עומדות במרכז הטרנספורמציה הדיגיטלית של הענף – וחברות שמאמצות אותן מוקדם יותר יהנו מיתרון תחרותי משמעותי. ConWize היא דוגמה לפלטפורמה ישראלית שמשלבת כמה מהכלים הללו – אומדן, תמחור וניהול מכרזים – בפתרון אחד מאוחד, שנבנה על הצרכים הספציפיים של שוק הבנייה המקומי.
טכנולוגיה 1: BIM – מידול מידע לבניין
BIM (Building Information Modeling) אינה עוד חידוש – היא הופכת לסטנדרט עבודה. BIM מאפשרת יצירת מודל תלת-ממדי דיגיטלי של הבניין שכולל לא רק גיאומטריה אלא גם נתוני עלות, לוחות זמנים, מפרטים טכניים ותחזוקה עתידית.
אנגליה מחייבת BIM בכל מבנה ציבורי מ-2016
ישראל צפויה להרחיב דרישות BIM בפרויקטי תשתיות ממשלתיים ב-2025–2026
חיסכון ממוצע: 5–10% בעלויות בנייה, 20% בשגיאות תכנוני
טכנולוגיה 2: ניהול אומדן ותמחור בענן
גיליונות Excel אינם מספיקים יותר כשמנהלים מספר פרויקטים מורכבים בו-זמנית. פתרונות ענן לאומדן מאפשרים גישה בכל מקום, שיתוף פעולה בזמן אמת ועדכון מחירים אוטומטי. פלטפורמת ConWize לאומדן ותמחור מייצגת את הדור הבא של כלים אלה: ממשק עברי, כתב כמויות מובנה, ניהול מכרזים ושליטה בתקציב – הכל מקום אחד.
חיסכון ממוצע בזמן אומדן: 35–50%
ירידה בשגיאות תמחור: עד 70%
זמינות מהשטח: עדכון ומעקב ישירות מהסמארטפון
טכנולוגיה 3: פלטפורמות ניהול פרויקטים בענן
כלים כמו Procore, PlanGrid ומקבילות ישראליות מאפשרות ניהול לוחות זמנים, עבודות וחוזים מרכזי – עם ניראות מלאה לכל בעלי העניין בפרויקט. לפי Dodge Data & Analytics, חברות שמשתמשות בפלטפורמות ניהול פרויקטים מדווחות על עמידה בלוחות זמנים גבוהה ב-30% לעומת חברות שאינן משתמשות.
ניהול RFI ותוכניות ישירות מהאפליקציה
תיעוד אוטומטי של כל החלטה ואירוע בשטח
דשבורד סטטוס לכל קבלן ומשימה
טכנולוגיה 4: ניתוח נתוני שטח ו-IoT
חיישנים, מצלמות ומכשירי IoT שמוצבים באתר הבנייה מאפשרים מעקב בזמן אמת אחר התקדמות עבודות, שימוש בציוד ותנאי בטיחות. הנתונים מוזנים לפלטפורמות ניתוח שמאפשרות לזהות עיכובים, בזבוז ומפגעי בטיחות לפני שהם הופכים לבעיות.
ניטור ממשי של שעות עבודה ונוכחות
מעקב GPS אחר ציוד וכלי רכב
התראות בטיחות אוטומטיות
טכנולוגיה 5: בינה מלאכותית לתמחור ואומדן
הדור הבא של כלי האומדן משלב בינה מלאכותית שמנתחת פרויקטים קודמים ומחירי שוק כדי לייצר אומדנים מדויקים יותר. מערכות AI מסוגלות לזהות חריגות, להצביע על סיכוני עלות ולהציע חלופות תכנוניות זולות יותר – כל זאת בשבריר מהזמן שצוות אנושי היה זקוק לו.
לפי סקר Autodesk מ-2024, 68% ממנהלי הפרויקטים בעולם מאמינים ש-AI תהיה מרכזית בתמחור ואומדן תוך שלוש שנים.
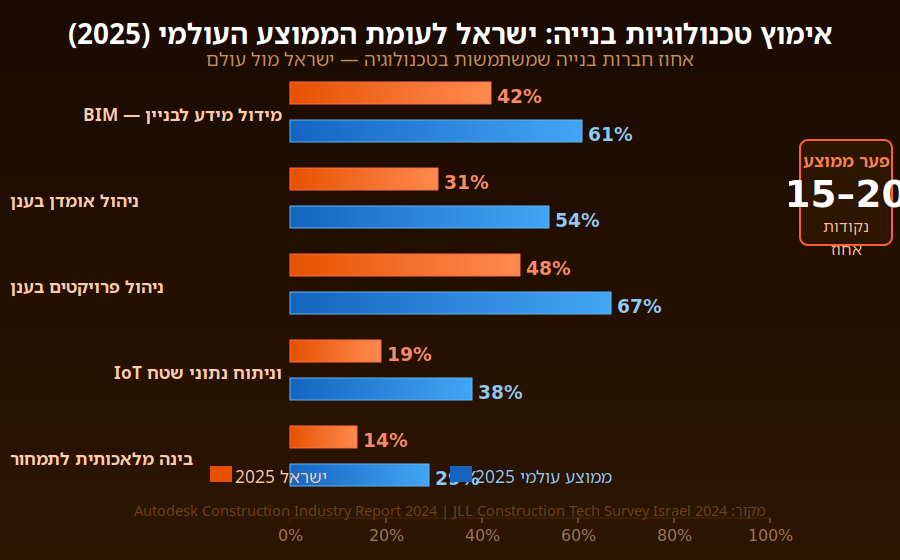
טבלת השוואה: שיעורי אימוץ טכנולוגיות בנייה בישראל (2025)
| טכנולוגיה | שיעור אימוץ (ישראל) | שיעור אימוץ (עולמי) |
| BIM | 42% | 61% |
| ניהול אומדן בענן | 31% | 54% |
| ניהול פרויקטים בענן | 48% | 67% |
| IoT וניתוח שטח | 19% | 38% |
| AI לתמחור ואומדן | 14% | 29% |
מקור: Autodesk Construction Industry Report 2024; JLL Construction Tech Survey Israel 2024
מה שוק הבנייה בישראלי צריך לדעת
ישראל מאמצת טכנולוגיות בנייה בקצב איטי יותר מהממוצע העולמי – אך הפער מצטמצם. הנהגת מחייבת BIM בפרויקטים ציבוריים, עלייה בהיקפי הבנייה ותחרות גוברת על כוח אדם מיומן יוצרים לחץ שמאיץ את קצב האימוץ. חברות שיתחילו את המעבר הדיגיטלי עכשיו ייהנו מיתרון ראשון-מגיע שיהיה קשה לשחזר בעוד שלוש שנים.
התחילו בכלי ה-ROI המהיר ביותר: ניהול אומדן ותמחור דיגיטלי
צרו מסד נתונים פנימי של עלויות מפרויקטים קודמים
השקיעו בהכשרת צוות – הטכנולוגיה טובה בדיוק כמו האנשים שמשתמשים בה
בחרו פלטפורמה עם תמיכה מקומית ותיעוד בעברית
סיכום
הטרנספורמציה הדיגיטלית של שוק הבנייה הישראלי אינה שאלה של ‘אם’ אלא של ‘מתי’. הכלים שפעם היו נחלת חברות הבנייה הגדולות ביותר בעולם הפכו נגישים, מותאמים מקומית ומוכחים בשטח. חברות שישכילו לאמץ טכנולוגיות אלה יוכלו לנהל פרויקטים מורכבים יותר, לשמור על שולי רווח בריאים ולספק ללקוחות שלהן רמת מקצועיות שהמתחרים לא יוכלו להציע. זהו הרגע לפעול
Business Solutions
Conwize: Quoting Software for Builders with Integrated Construction Bid Management
In competitive construction markets, how you quote is as important as what you quote. Builders and contractors that produce fast, accurate, professionally presented quotations – and that track their bidding activity systematically through a structured construction bid management software – consistently win more work at better margins than those who treat quoting as a reactive administrative task. Conwize is built on this insight, providing quoting software for builders that transforms pre-construction commercial operations from a pressure point into a competitive advantage.
The Commercial Cost of Inadequate Quoting Tools
The construction industry’s quoting and bidding function consumes a substantial proportion of a contracting business’s overhead – estimating teams, bid coordinators, quantity surveyors, and management time all contribute to the cost of pursuing work that may or may not be won. Industry benchmarks suggest that the estimating cost per bid ranges from 0.1% to 0.5% of project value for sophisticated estimating operations, and considerably more for businesses using manual, inefficient processes.
The opportunity cost of inadequate quoting software for builders is even larger. Teams hampered by slow, manual quoting processes cannot pursue as many tenders as the market makes available. Errors in manually assembled quotes – whether missed cost items, transposition errors, or outdated subcontractor prices — either cost margin when not caught before submission or cost the bid when detected by the client during evaluation. And the lack of systematic construction bid management means that business development intelligence – which project types are most winnable, which clients award most reliably, which geographies have the best margin potential – is never captured or analyzed.
Conwize addresses all three dimensions of this challenge: faster quoting through workflow automation, more accurate quotes through integrated subcontractor pricing, and richer bid intelligence through systematic pipeline management.
How Conwize’s Quoting Workflow Works for Builders
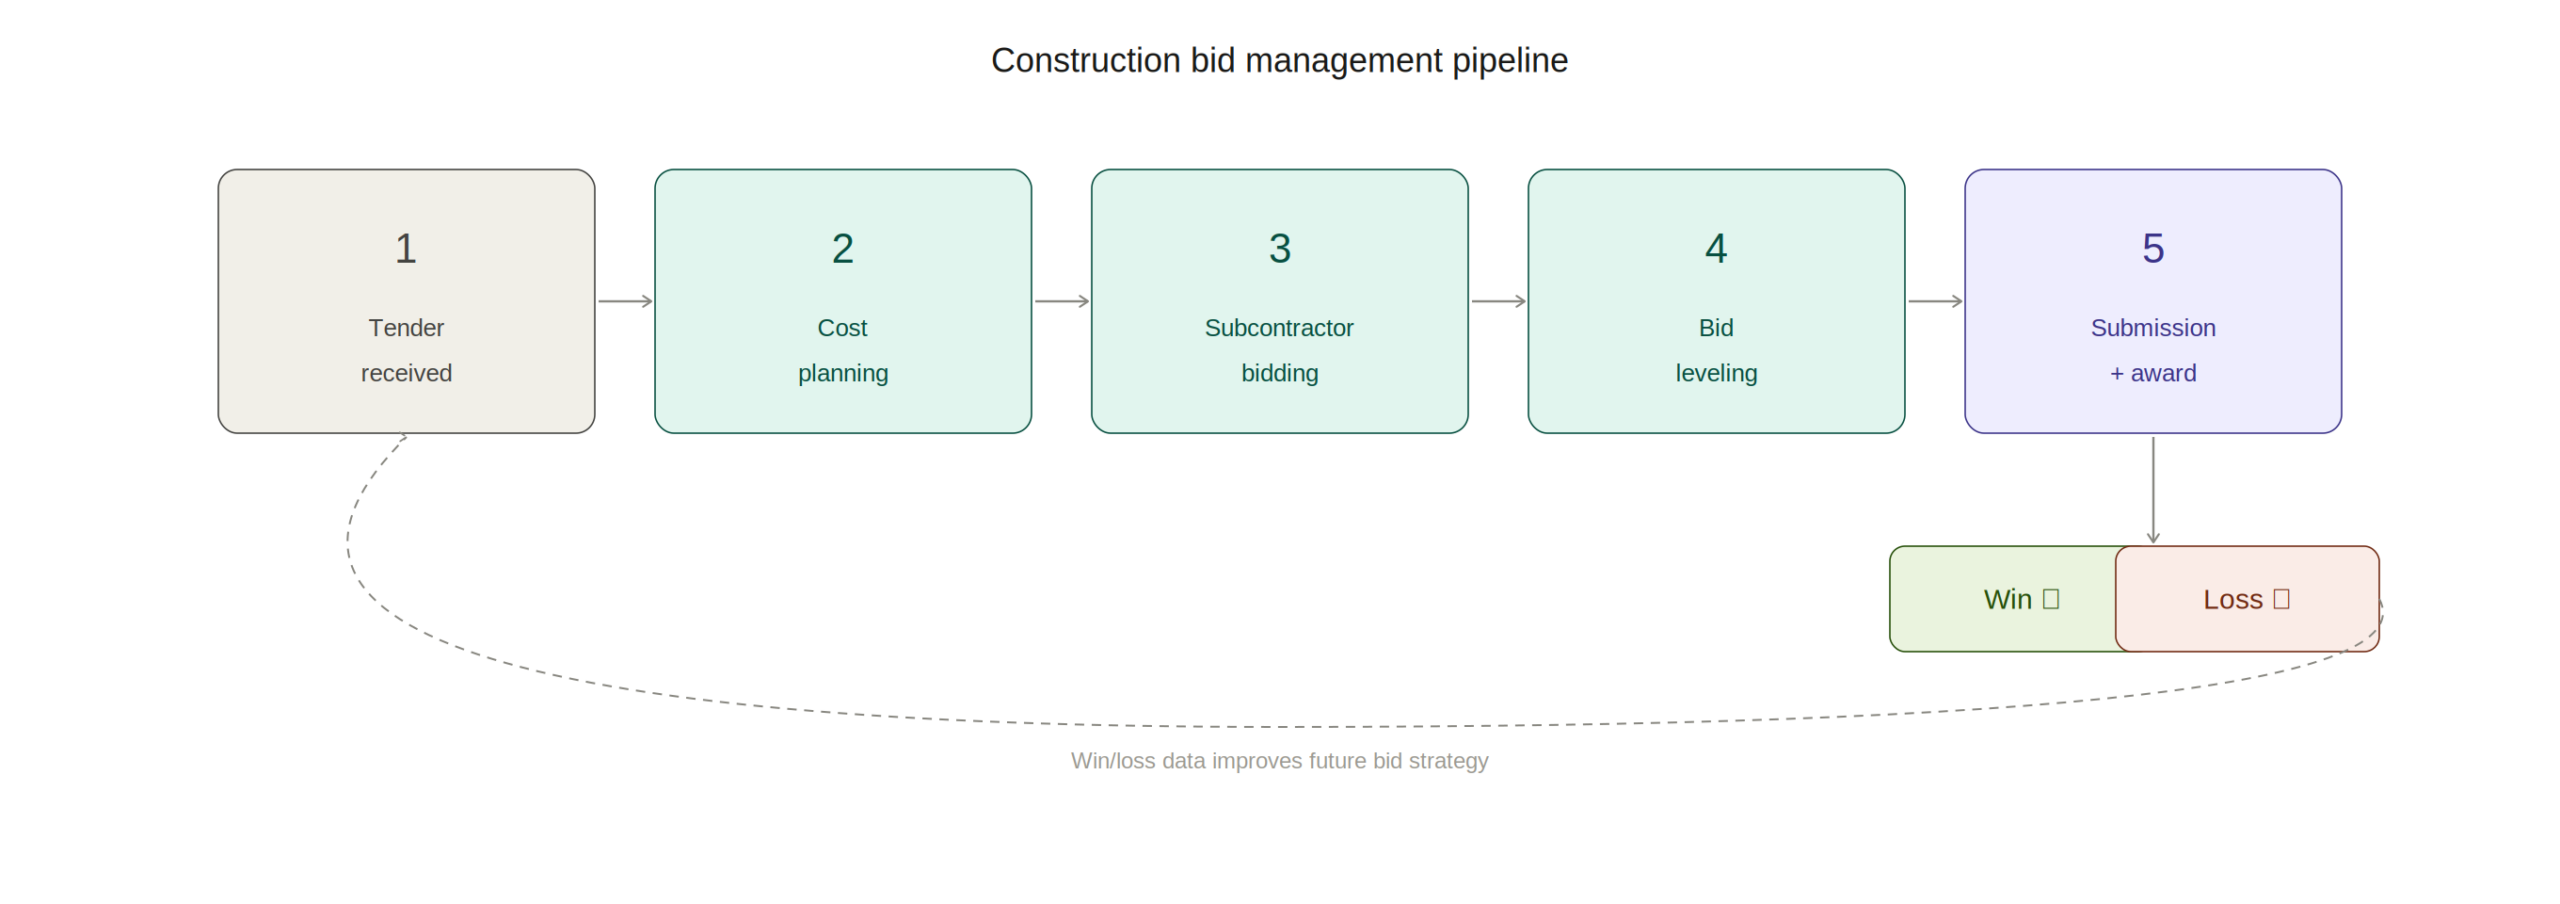
When a tender invitation arrives, Conwize’s quoting workflow begins with a single project setup action: the estimator creates a new project, loads the tender documents, and structures the scope into trade packages. From this point, the entire quoting process runs within Conwize – with no information escaping into external spreadsheets or email threads that cannot be tracked or controlled.
The subcontractor quotation process — typically the most time-consuming element of any builder’s quoting workflow – is where Conwize delivers its most immediate time savings. Scope packages are prepared within the platform and distributed to selected subcontractors in a single action. Subcontractors receive a structured invitation with all relevant documents attached. Response receipt is tracked automatically. Reminder notifications go out to non-responding subcontractors without manual chasing. And received quotations are loaded into Conwize’s bid comparison interface for structured analysis.
The bid comparison and leveling interface presents all received subcontractor quotations side by side against the scope items, automatically calculating adjusted totals that account for scope gaps, and flagging the most competitive compliant offer for each package. What takes a day or more of manual analysis in a spreadsheet is accomplished in Conwize in under an hour — with a complete, documented audit trail of the comparison.
Construction Bid Management: The Strategic Layer Above Quoting
Quoting individual tenders is a tactical activity; construction bid management is the strategic framework that ensures the quoting function serves the business’s commercial objectives. Effective bid management means having a clear, systematically applied bid/no-bid decision process, a structured pipeline of active tenders with visibility of deadlines and resource requirements, and a rigorous post-submission win/loss analysis process that feeds continuous improvement of the bidding strategy.
Conwize’s bid management capability provides all three elements. The pipeline dashboard gives construction directors and business development managers a real-time view of every active tender – project value, client, submission deadline, responsible estimator, and current status. This visibility enables informed bid/no-bid decisions on new opportunities and supports resource allocation decisions that ensure the most commercially important bids receive appropriate attention.
For a detailed breakdown of how systematic construction bid management transforms pre-construction commercial operations, Conwize’s dedicated article on construction bid management covers the key components — from pipeline design to win/loss analysis frameworks — in detail. The discipline of managing bids systematically rather than reactively is one of the most significant changes a construction business can make to its commercial performance.
Subcontractor Management Within the Quoting Platform
The quality of a builder’s subcontractor network is a direct determinant of the quality of their quotations – and managing that network effectively requires more than a contacts list. Conwize’s subcontractor database tracks each subcontractor’s trade coverage, geographic range, response rate, historical pricing competitiveness, and performance on awarded projects — providing the intelligence needed to assemble the best tender list for each trade package on each new project.
Over time, this intelligence compounds: estimators can see which subcontractors consistently respond with competitive prices for specific trade types, which tend to submit incomplete scope, and which have the highest award rates. This data-driven tender list selection is a significant quality improvement over the informal, relationship-based subcontractor selection that most builders currently practice.
The Conwize subcontractor portal – through which subcontractors receive invitations, submit quotations, and track their own bid history – is designed for ease of use from the subcontractor’s perspective, increasing response rates and improving the quality of received quotations.
Frequently Asked Questions
Q1: What is quoting software for builders and how does it differ from generic estimating tools?
A: Quoting software for builders is specifically designed for the construction quoting workflow – managing the complete process from scope definition through subcontractor bid management to submission document generation. Generic estimating tools focus on cost calculation; purpose-built quoting software manages the entire commercial workflow surrounding that calculation.
Q2: What is construction bid management and why is it important?
A: Construction bid management is the systematic process of tracking, coordinating, and analyzing the full bidding lifecycle – from tender identification and bid/no-bid decision through to submission, award, and win/loss review. Systematic bid management transforms bidding from a reactive activity into a managed commercial function with measurable performance improvement over time.
Q3: How does Conwize’s quoting workflow save time for builders?
A: Conwize automates the most time-consuming elements: subcontractor invitation and tracking (replacing manual email management), bid leveling (replacing manual spreadsheet comparison), and submission document generation (replacing manual reformatting). These automations typically reduce quoting time by 30-50% per tender.
Q4: Can Conwize track multiple simultaneous tenders in the bid pipeline?
A: Yes. Conwize’s pipeline dashboard displays all active tenders – value, deadline, client, status, and responsible estimator – in a single management view. This enables directors to allocate estimating resources, make bid/no-bid decisions, and track portfolio-level bidding activity in real time.
Q5: How does Conwize support post-bid win/loss analysis?
A: Conwize records bid outcomes — win/loss status, awarded value, client, project type, and geographic location – enabling systematic analysis of win rates by project type, client sector, tender value range, and other dimensions. This intelligence informs continuous improvement of bidding strategy and target market selection.
Q6: Does Conwize help with subcontractor response rates on quotation requests?
A: Yes. Conwize sends automated follow-up reminders to subcontractors who have not responded to quotation invitations, significantly improving response rates without manual chasing. The subcontractor portal provides a simple, accessible submission interface that further encourages response.
Q7: Is Conwize suitable for both residential builders and commercial contractors?
A: Conwize serves both residential builders managing volume quoting workflows and commercial contractors pursuing complex multi-trade tenders. The platform scales from straightforward residential quotations to sophisticated commercial BOQ-based estimates with comprehensive subcontractor bid management.
Waterproof Cases and Hard Shell Carrying Cases: What the Ratings Actually Mean
What Is IOR and EOR? How to Choose the Right IOR Provider for Tech Hardware
What Is a Venture Capital Fund? How VC Funds Actually Work

-
 Business Solutions2 years ago
Live Video Broadcasting with Bonded Transmission Technology
-
 Business Solutions1 year ago
The Future of Healthcare SMS and RCS Messaging
-
 Business Solutions2 years ago
2-Way Texting Solutions from Company Message Services
-
 Business Solutions2 years ago
Communication with Analog to Fiber Converters & RF Link Budgets
-
 DSRC Communication1 year ago
The Crossroads of Connectivity: DSRC vs. C-V2X Technologies in Automotive Communication
-
 Business Solutions2 years ago
Wholesale SMS Platforms with OTP Services
-
 Business Solutions2 years ago
Choosing the Right B2B Digital Marketing Agency: A Guide
-
 3D Technology1 year ago
How Multispectral Cameras Advance Book Scanning