
Business Solutions
The Basics of OTP SMS Texting

One-Time Passwords (OTP) have become indispensable in ensuring secure user verification processes, and OTP SMS remains the most popular way to deliver these codes. OTP text messages provide a simple, effective way for platforms to validate the identity of users during login, transactions, or other secure processes. This approach to security relies on a code sent via SMS, ensuring that only the intended recipient can complete the authentication process.
OTP SMS stands out because of its user-friendly approach—almost everyone carries a mobile phone capable of receiving SMS. The universality of SMS as a communication medium means that OTP texts are accessible to a broad audience without the need for additional software or special devices. This accessibility makes OTP SMS a go-to solution for companies looking to enhance user security while keeping the user experience smooth and straightforward.
One of the key benefits of OTP text messages is their limited validity. OTPs are time-sensitive, often valid for just a few minutes, which ensures that the authentication process remains secure even if the message is intercepted. This temporary nature adds an additional layer of protection, reducing the window of opportunity for cybercriminals to misuse the code.
The Anatomy of an OTP: What Makes It Tick?
To understand why OTP SMS is effective, it’s essential to know what makes an OTP functionally secure. An OTP, by design, is a unique sequence of numbers or characters that is valid only for a single use. The OTP text typically ranges between four and eight digits, making it both secure and user-friendly, as users can enter it easily without confusion.
The randomness of an OTP is one of its most critical components. OTP generation leverages algorithms that ensure the code cannot be easily predicted. Algorithms like HMAC-based OTP (HOTP) and Time-based OTP (TOTP) play a pivotal role in generating these codes, ensuring that each one is unique and valid only within a specific time window. The result is a secure and dynamic code that is virtually impossible for attackers to guess through conventional means.
Moreover, the temporal aspect of OTP SMS is equally crucial. OTP texts usually expire within 30 seconds to a few minutes, adding a dynamic component to their security. This limited window of validity means that even if an OTP is intercepted, it becomes useless after its short lifespan ends. The combination of algorithmic randomness and time restriction makes OTP SMS a formidable tool for preventing unauthorized access.
Why OTP SMS? Advantages in Authentication
OTP SMS remains a preferred choice for authentication due to its simplicity and effectiveness. Unlike traditional passwords, which are static and vulnerable to brute force attacks or leaks, OTP texts are dynamic and used only once. This one-time nature makes them significantly more secure, especially for protecting sensitive data like banking information or private communications.
A significant advantage of OTP SMS is its familiarity. Users are already accustomed to receiving SMS messages, and integrating OTPs into this channel means that there is no learning curve involved. This makes adoption easier for both individuals and businesses, minimizing friction in the authentication process.
Additionally, OTP SMS is cost-effective for businesses. Unlike other methods that require hardware tokens or specialized software, using SMS takes advantage of existing telecommunications infrastructure. With minimal upfront investment and maintenance requirements, companies can roll out OTP-based authentication to their entire user base quickly and efficiently, thereby enhancing security without incurring prohibitive costs.
The Role of OTP SMS in Multi-Factor Authentication
Multi-Factor Authentication (MFA) has become the gold standard for securing online accounts, and OTP SMS plays an essential role in this context. MFA requires users to provide two or more verification factors to prove their identity, and OTP text messages serve as an ideal second factor. Typically, the first factor is something the user knows (like a password), while the second is something they have (like an OTP sent via SMS).
By using OTP SMS as part of MFA, companies can significantly reduce the likelihood of unauthorized access. Even if an attacker manages to steal a user’s password, they still need access to the user’s mobile phone to receive the OTP, adding a critical additional barrier. This layered security approach makes it much more difficult for attackers to gain access, even if one layer of security is compromised.
Despite some concerns about the vulnerability of SMS, it remains a practical choice for many organizations because of its broad accessibility and ease of implementation. Many users are familiar with the process of receiving and entering OTPs, making it an effective and user-friendly option for enhancing account security across various platforms.
Navigating the Pitfalls: Avoiding OTP Fraud
While OTP SMS is a powerful security tool, it is not without vulnerabilities. One of the primary challenges is the potential for phishing attacks. In these attacks, cybercriminals trick users into revealing their OTP by impersonating a legitimate service. Once the OTP is handed over, the attacker can use it to gain unauthorized access to the user’s account.
To mitigate the risks of OTP fraud, user education is paramount. Users should be aware of the importance of never sharing their OTP texts with anyone, even if they appear to be from a legitimate source. Organizations can also take steps to prevent fraud by implementing anti-phishing tools and incorporating warning messages into OTP SMS, reminding users never to share their codes.
In addition, security measures like monitoring unusual activity, rate limiting, and requiring additional verification for high-risk transactions can help reduce the risk of OTP-based attacks. By recognizing and mitigating these vulnerabilities, organizations can make their OTP SMS systems more robust and resistant to fraud.
Integrating OTP SMS with Your Tech Stack
Integrating OTP SMS with an existing tech stack can significantly enhance an organization’s security framework. However, the integration process requires careful consideration to ensure compatibility and scalability. For instance, businesses must select an OTP SMS provider that offers reliable and fast message delivery across different mobile carriers.
The process often involves integrating an API that facilitates OTP SMS sending, which allows seamless communication between the business’s application and the SMS gateway. Ensuring that this integration is secure is critical. Encryption must be used to protect OTPs during transmission, and rate limits should be set to prevent abuse.
Scalability is another essential consideration. Businesses with a large user base must ensure that their OTP SMS provider can handle peak demands, especially during high-traffic events such as flash sales or product launches. Choosing a service with guaranteed uptime and low latency ensures that users receive their OTP texts promptly, minimizing friction during the authentication process.
Global Reach: OTP SMS in International Contexts
The use of OTP SMS across international borders introduces unique challenges. Varying carrier fees, regulatory restrictions, and differing network capabilities can all impact the delivery and reliability of OTP texts. For businesses with a global user base, ensuring that OTP SMS is delivered reliably and consistently to users in different regions is crucial for maintaining trust and security.
Different countries have varying regulations regarding SMS communications, particularly in terms of user consent and data privacy. Organizations must navigate these regulations to remain compliant while providing OTP services. Working with an SMS provider that has experience in international markets can help businesses overcome these challenges, ensuring consistent delivery times and minimizing the risk of messages being blocked or delayed.
Another consideration for global OTP SMS delivery is language. When sending OTP texts to users in different countries, localization becomes important. Businesses should ensure that the language of their OTP SMS messages is suitable for the recipient, improving user experience and reducing confusion.
Case in Point: Innovations Driving OTP SMS Forward
The technology behind OTP SMS is continually evolving, driven by the need for better security and user experience. One area of innovation is the integration of biometric verification with OTP SMS. By combining fingerprint or facial recognition with OTPs, businesses can offer an even higher level of security without sacrificing convenience.
Machine learning and artificial intelligence are also being utilized to enhance the OTP SMS process. AI algorithms can analyze user behavior and flag any unusual activity, which may indicate a potential security breach. By integrating AI into the OTP process, organizations can proactively address security threats before they result in a data breach.
Another innovation driving the evolution of OTP SMS is the use of encrypted SMS channels. Unlike traditional SMS, which can be vulnerable to interception, encrypted SMS ensures that OTP texts are transmitted securely, making it even harder for attackers to intercept and misuse them.
Towards a Safer Future: The Evolution of OTP SMS
As cyber threats become more sophisticated, the methods we use to protect sensitive information must also evolve. OTP SMS remains an integral part of the security landscape due to its accessibility, simplicity, and effectiveness. However, advancements in technology and the growing complexity of cyber threats mean that OTP SMS must continue to adapt.
Looking forward, we can expect OTP technologies to be more deeply integrated into multi-factor authentication systems, possibly working alongside biometric data or even behavioral analytics. Innovations like encrypted messaging, AI-driven fraud detection, and dynamic risk-based authentication will likely become standard features of OTP SMS solutions.

Business Solutions
Long-Conical Peppers: How Heat-Tolerant Sweet Varieties Are Changing the Long Red Pepper

| Key Takeaways
• Long-conical peppers are slender, tapered sweet peppers (Capsicum annuum) usually sold fully red and positioned as a premium culinary format. • Very little pepper fruit set occurs above 90°F during the day or below 60°F at night, and fruit that sets above 85°F is often small and misshapen. • Parthenocarpy, fruit development without fertilization, helps some pepper lines keep setting fruit when heat reduces pollen viability. • Retail long red peppers are typically harvested at about 90% red color before noon and precooled to 10 to 12°C immediately after picking. |
What are long-conical peppers?
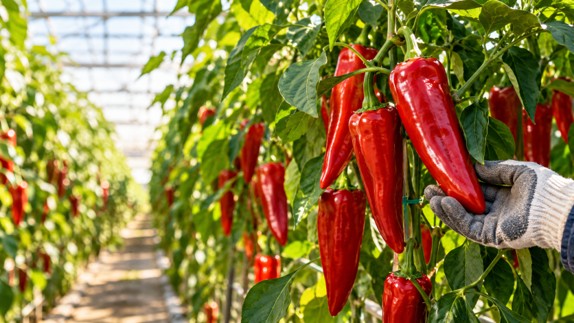
Long-conical peppers are sweet peppers (Capsicum annuum) with a slender, elongated fruit that tapers from a broad shoulder to a narrow point, usually harvested fully red. They belong to the same species as the bell pepper but carry no meaningful heat, so produce buyers place them with sweet red peppers rather than chiles. Their shape is the selling point: a long red pepper reads as premium on the shelf, slices into even rings, and roasts whole without collapsing. Breeders now position long-conical sweet peppers as a gourmet format. BreedX, a seed company specializing in pepper and tomato breeding, describes its long-conical line as sleek and red with intense sweetness, aimed at chefs and at retailers looking for a visual alternative to the standard blocky bell.
For growers the interest is less about looks and more about agronomy. Long peppers are being bred alongside snack and mini formats inside the same seedless sweet pepper programs, which means traits like heat tolerance, yield stability and disease resistance are moving into this shape class quickly. That is what makes the category worth a closer look in 2026, when hotter summers are putting pressure on every pepper crop that relies on reliable fruit set.
Why does heat stress matter so much for long red peppers?
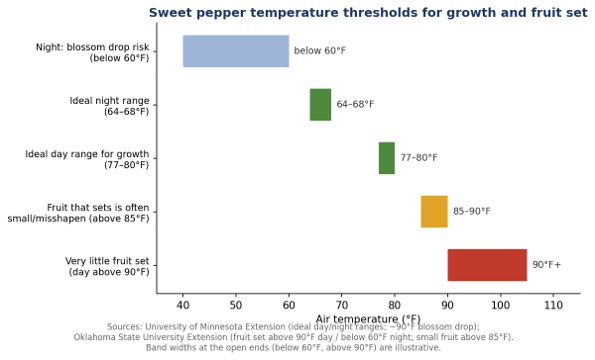
Heat stress matters because pepper flowers fail to set fruit once daytime temperatures pass roughly 90°F (32°C), and fruits that do set above about 85°F tend to be small and poorly shaped. For an elongated pepper, misshapen fruit is a direct loss: a long-conical pepper that sets short, curved or uneven is downgraded even if the plant is healthy. Oklahoma State University’s extension fact sheet on pepper production puts the limits plainly: very little fruit set happens above 90°F during the day or below 60°F at night, and some small-fruited pungent peppers tolerate high-temperature fruit set better than bell types.
The cool end of the range is just as important. Michigan State University Extension notes that night temperatures below 60°F also cause blossom drop, and that a shortage of water at bloom time can produce the same failure. The University of Minnesota Extension gives the ideal window for vegetative growth as 77 to 80°F during the day and 64 to 68°F at night, with blossom and fruit drop appearing near 90°F once plants flower.
Research on Capsicum annuum confirms how narrow the margin is. A 2022 study in the SABRAO Journal of Breeding and Genetics reported that a threshold of about 32.9°C significantly reduced chili pepper production, with heat cutting pollen viability and increasing flower abortion. Pollen development is the weak link: when it fails, the flower drops or the fruit develops unevenly.
How do breeders build heat tolerance into sweet peppers?
Breeders build heat tolerance by selecting lines that keep setting fruit when pollen performance declines, and one of the most effective routes is parthenocarpy, the ability to develop fruit without fertilization. An older Taiwanese study on hot pepper lines found one line that kept a high fruit set at 35/30°C day/night despite low pollen viability, and the researchers suggested parthenocarpy as the likely reason. A plant that does not depend on viable pollen to form fruit is, almost by definition, less exposed to the heat-driven pollen failure described above.
This is the logic behind seedless sweet pepper programs. One breeder of seedless pepper lines bred for heat and cold tolerance says that without seeds inside the fruit, the plant’s energy is redirected to fruit setting, and that its varieties maintain production under high and low temperature extremes and high humidity. The same breeder says all its lines are developed through traditional, non-GMO breeding and supplied to growers as seed rather than seedlings. Those are breeder claims rather than independent trial results, so growers should still test any new long-conical variety in their own climate before scaling.
How do long-conical peppers compare with other sweet pepper formats?
Long-conical peppers sit at the premium, culinary end of the sweet pepper range, while blocky and snack formats cover stuffing, slicing and convenience snacking. The comparison below summarizes how the main formats are typically positioned. Size figures are only given where a breeder has published them.
| Format | Shape and size | Typical use |
| Long-conical | Slender, tapered, elongated red fruit | Gourmet dishes, roasting whole, plated presentation |
| Midi-blocky | Medium-sized, blocky | Stuffing and slicing |
| Mini-kapia | Snack-sized and elongated | Crunchy, sweet snacking |
| 1-bite | 4 to 7 cm, bite-sized | Lunchboxes and whole-fruit snacking |
Within a single seedless program, the long-conical type is often bred to the same standard as the snack types: high yield, tolerance to extreme temperatures and resistance to key plant diseases. The difference is the market it serves. A buyer for a food-service distributor will judge a long pepper on length, straightness and wall color; a snack buyer will judge a mini pepper on crunch, uniformity and pack-out.
When should long-conical peppers be harvested?
Long-conical peppers grown for retail are usually picked at about 90% red color in the morning, or at around 50% color when extra shelf life matters more than full ripeness. That guidance comes from a five-step harvest and post-harvest protocol published for sweet and seedless peppers, which recommends harvesting before 12:00 PM, precooling fruit immediately to 10 to 12°C, and packing into macro- or micro-perforated plastic bags that keep air moving and prevent condensation.
After packing, the same protocol calls for bringing fruit back down to 10°C before transport and keeping an unbroken cool chain to avoid dehydration. Michigan State University Extension gives a similar storage target for peppers: 45 to 50°F with 85 to 90% relative humidity. For an elongated fruit, careful handling also prevents tip breakage and bruising along the narrow end, which shows quickly on a red skin.
Are long red peppers nutritionally different from bell peppers?
Long red peppers are fully ripe sweet peppers, so their nutrition tracks that of ripe red bell peppers, which USDA data puts at 127.7 mg of vitamin C per 100 g raw. Ripening is the main driver: red sweet peppers are ripened green peppers and carry more sugar, which is why long red types taste noticeably sweeter than green ones. Shape itself does not change nutritional value in any documented way, but the long format encourages raw use in salads and as crudités, where vitamin C is preserved because no cooking is involved.
What should growers look for when choosing a long-conical variety?
Growers should prioritize consistent fruit set under their local temperature extremes, uniform length and straightness, and documented disease resistance, in that order. Heat is the most common reason long peppers fail commercially, so a variety’s record in hot-season trials matters more than its appearance in a catalog photo. The University of Minnesota Extension notes that heat-related blossom drop shows up as soon as plants flower in hot weather, which means the first set is where weak varieties are exposed.
Beyond genetics, the same basics apply as for any sweet pepper: steady irrigation through bloom, shade or ventilation to keep canopy temperatures below the 90°F danger zone, and harvest timing matched to the market. A long-conical pepper that is bred to set fruit under stress, picked at the right color and cooled quickly is the format’s best case: a premium red pepper that holds its shape from the greenhouse to the plate.
Frequently Asked Questions
Are long-conical peppers spicy?
No, long-conical peppers are sweet peppers in the species Capsicum annuum and are bred for sweetness rather than heat.
What temperature stops pepper plants from setting fruit?
Pepper fruit set drops sharply when daytime temperatures exceed about 90°F (32°C) or night temperatures fall below 60°F (16°C).
How should long red peppers be stored after harvest?
Long red peppers keep best when cooled quickly after picking and stored at about 45 to 50°F (7 to 10°C) with 85 to 90% relative humidity.
Why are some sweet peppers bred to be seedless?
Seedless sweet peppers are bred for convenience and, according to breeders, because a plant that does not invest energy in seeds can direct more of it to setting fruit.
|
Key Takeaways
|
What is a venture capital fund, in plain terms?
A venture capital fund is a pool of capital, contributed by investors and managed by a dedicated investment team, used to fund private companies, typically early-stage or growth-stage businesses with high growth potential, in exchange for an equity ownership stake. Unlike a bank loan, venture capital doesn’t need to be repaid on a fixed schedule; instead, the fund’s investors participate in the company’s future upside (or downside) alongside its founders. The fund’s managers, often called general partners, make the actual investment decisions on behalf of the fund’s investors, who are typically called limited partners.
How is a typical VC fund actually structured?
The overwhelming majority of venture capital funds are structured as limited partnerships. General partners (GPs) manage the fund, source and evaluate investment opportunities, sit on portfolio company boards, and make the calls about which companies to fund and when to exit. Limited partners (LPs), which can include pension funds, university endowments, family offices, and wealthy individuals, commit capital to the fund but generally aren’t involved in individual investment decisions. In exchange for their capital, LPs typically pay the fund a management fee, often around 2% of committed capital annually, plus a share of the fund’s profits, commonly 20%, known as carried interest.
What does a VC fund’s lifecycle actually look like?
A traditional VC fund isn’t a permanent, evergreen pool of capital; it has a defined lifecycle, typically spanning 8 to 12 years from first close to final wind-down.
| Fund lifecycle stage | What actually happens |
|---|---|
| Fundraising and first close | The fund raises committed capital from LPs before making its first investments. |
| Investment period | Typically the first 3 to 5 years, during which the fund makes its initial investments into portfolio companies. |
| Active management and follow-on | The fund supports existing portfolio companies, often participating in follow-on funding rounds as those companies grow. |
| Exit and distribution | The fund realizes returns through acquisitions, IPOs, or other exit events, and distributes proceeds back to LPs. |
How large has the global venture capital market actually become?
The scale of capital flowing through venture capital funds globally has grown enormously over the past two decades. IMARC Group’s venture capital investment market analysis values the global market at $284.8 billion in 2023, projected to reach $1,310.8 billion by 2032, a compound annual growth rate of 17.9%. That growth reflects the increasing role venture capital plays in fostering innovation and entrepreneurship globally, with software consistently commanding the largest share of capital deployed, and follow-on funding, capital deployed into companies a fund has already backed, generally outpacing first-time venture funding.
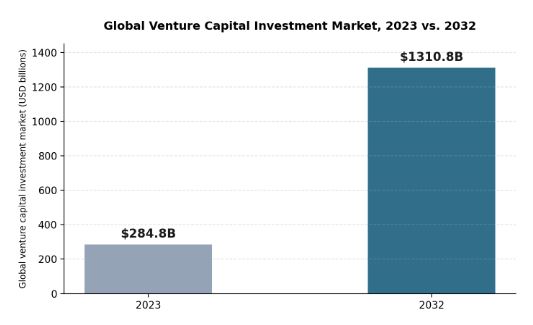
Global venture capital investment market size, 2023 versus 2032, according to IMARC Group.
Are all venture capital funds structured the same way?
No, and understanding the alternatives matters for founders evaluating which type of investor actually fits their company. Elron Ventures’ own description of its model illustrates one such alternative directly: rather than a traditional limited partnership raising committed capital from external LPs, Elron operates as a publicly traded technology investment company, one of Israel’s leading investment firms since 1961, deploying capital through two core growth engines, early-growth technology investments and an M&A-driven growth strategy focused on acquiring early-stage dual-use technology companies. That structure gives a company like Elron more flexibility in its investment horizon and capital deployment than a fund bound by a fixed limited-partnership lifecycle, since it isn’t operating against the same fundraising and wind-down clock a traditional 8-to-12-year fund faces.
What does ‘early-growth’ investing actually mean, as distinct from seed or late-stage?
Venture capital funds typically specialize by stage, and the terminology matters for founders trying to identify the right fit. Seed-stage funds back companies at their earliest, often pre-revenue stage, when the primary risk being underwritten is whether the founding team and product concept can find genuine traction. Early-growth investing, the stage many established Israeli VC funds focus on, targets companies that have already demonstrated initial product-market fit and are looking to scale that traction into a larger, more durable business. Late-stage and growth-equity funds, by contrast, back companies with established revenue and a clearer path to an exit event, often writing much larger checks at higher valuations. A fund’s stated stage focus should shape which companies actually approach it for funding, since a seed-stage pitch to a late-stage growth fund, or vice versa, rarely leads anywhere productive.
What should a founder actually understand before approaching a VC fund?
- What stage does the fund actually invest at? Confirm this matches your company’s current stage before spending time on outreach.
- What sectors or technologies does the fund focus on? Many funds specialize deeply, and a fund’s public messaging usually signals this clearly.
- Does the fund lead rounds, or only participate alongside a lead investor? This affects how much capital and support you can expect from that single relationship.
- What does the fund actually offer beyond capital? Strategic partnerships, sector expertise, and portfolio company networks can matter as much as the check size itself.
How does a VC fund actually decide when to exit an investment?
Exit timing is rarely a unilateral decision made purely on a fund’s own schedule; it emerges from a mix of the portfolio company’s own trajectory, market conditions, and the fund’s own lifecycle pressure. A fund nearing the end of its stated term has real incentive to push toward a liquidity event, an acquisition or IPO, since its own LPs expect distributions within a reasonably predictable timeframe rather than an indefinite hold. At the same time, a fund that exits too early can leave significant value on the table if a portfolio company’s growth trajectory was only just accelerating. Board seats, which many VC funds negotiate as part of their investment terms, give fund managers a formal voice in these exit timing conversations, rather than leaving the decision entirely in founders’ hands.
What does ‘dry powder’ actually mean, and why does it matter for founders?
Dry powder refers to capital that investors have already committed to a fund but that the fund hasn’t yet deployed into portfolio companies. A large pool of dry powder sitting across a market’s VC funds is generally a positive signal for founders, since it suggests real capital is available and actively looking for a home, rather than funds having already committed most of their capacity to existing portfolio companies. That said, dry powder alone doesn’t guarantee a fund will actually write a check to any particular startup; it simply describes the scale of capital theoretically available, not how selectively or aggressively any specific fund is currently deploying it.
Frequently Asked Questions
What’s the difference between a general partner and a limited partner?
General partners (GPs) manage the venture capital fund, make investment decisions, and typically earn management fees and a share of profits (carried interest). Limited partners (LPs) contribute capital to the fund but aren’t involved in day-to-day investment decisions.
How long does a typical venture capital fund actually last?
Most traditional VC funds have a lifecycle of 8 to 12 years, covering an investment period, an active management and follow-on period, and an exit and distribution period, though extensions are common when portfolio companies need more time to reach an exit event.
Can a venture capital fund invest in a company more than once?
Yes, this is common and is typically referred to as follow-on investment, where a fund participates in later funding rounds of a company it has already backed, often to maintain its ownership percentage as the company raises additional capital.
Is a publicly traded technology investment company the same thing as a traditional VC fund?
Not exactly. A publicly traded technology investment company, like Elron Ventures, typically deploys its own balance sheet capital rather than raising committed capital from external limited partners, giving it a different capital structure and investment horizon than a traditional limited partnership fund.
| Key Takeaways
• Israeli tech companies raised roughly $3.1 billion across 98 rounds in Q1 2026, up 34% year over year, with foreign investors supplying 65.9% of that capital. • Cybersecurity accounted for about 40% of Israeli VC funding in Q1 2026, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period. • Some Israeli VC firms operate a standard direct-investment fund alongside a separate joint-venture or acquisition arm focused on a specific sector, such as defense technology. • Government co-investment programs dating back to the early 1990s helped seed Israel’s venture capital industry, contributing to a market that now supports many independently capitalized local funds. |
What makes Israeli venture capital firms operate differently from international investors?
Israeli venture capital firms tend to combine a deep local sourcing network in a small, densely connected tech ecosystem with an operating assumption that most portfolio companies will need to scale into markets, most commonly the US and Europe, from day one. That dual-market posture shows up structurally, not just in messaging. one firm’s public profile of its own history and philosophy describes decisions made “within days to a few weeks,” a pace that reflects how tightly connected the local investor and founder community is compared with larger, more geographically dispersed markets.
How large is Israel’s venture capital market right now?
Israeli tech companies raised about $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase year over year, with March 2026 alone accounting for roughly $1.2 billion of that total. Foreign investors supplied 65.9% of that capital, underscoring how dependent the local ecosystem is on international capital even as local firms do much of the early sourcing and structuring. Cybersecurity alone accounted for about 40% of funds raised in the quarter, while defense-tech’s share fell from roughly 8% in 2025 to under 1% in the same period, a reminder of how quickly sector allocation can shift.
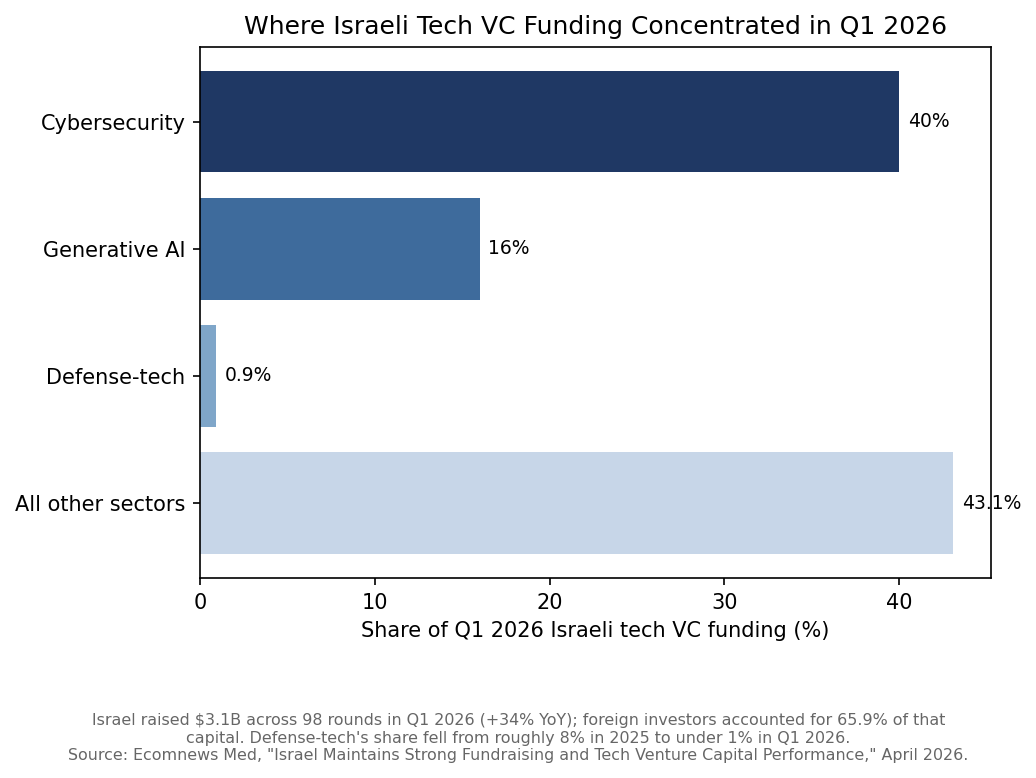
Sector breakdown of Israeli tech venture capital funding in Q1 2026, based on Ecomnews Med’s April 2026 reporting.
Why do some Israeli VC firms invest through more than one structure?
Some firms pair a standard direct-investment fund with a separate acquisition or joint-venture arm aimed at a specific sector, which lets them play both an early investor role and a strategic consolidator role in the same market. a portfolio spanning cybersecurity, deep and defense tech, medical devices, and enterprise software shows what that breadth looks like in practice, with more than 70 companies represented across active and exited positions. A defense-technology joint venture built with an established strategic partner is one example of this second structure, sitting alongside the firm’s conventional early-growth fund rather than replacing it.
How does sector specialization show up inside a single Israeli VC portfolio?
Sector specialization inside Israeli VC portfolios usually shows up as dedicated teams or sub-funds for a firm’s strongest local sourcing advantage, most often cybersecurity, layered underneath a broader generalist mandate. a dedicated cybersecurity portfolio segment and a medical-device investing track record spanning cardiovascular, orthopedic, and diagnostic devices illustrate two very different specializations coexisting inside the same firm, each drawing on a different regulatory and go-to-market path.
What role does government policy play in Israel’s VC ecosystem?
A government-funded program launched in 1993 played a documented role in seeding Israel’s venture capital industry by matching private investment at a set ratio, rather than by investing directly on its own. Under that program, the government allocated $100 million in total, $80 million of which matched foreign and domestic investment at roughly a 40% ratio so outside firms could establish their own funds inside Israel, with most of those funds later repurchasing the government’s stake within five years. See a historical summary of that matching-fund program and its transition to private ownership in 1997 for how that early policy groundwork is one reason the ecosystem now supports many independently capitalized local funds rather than depending on a handful of foreign offices, even though foreign capital still supplies the majority of dollars invested today.
Frequently Asked Questions
How much venture capital did Israeli tech companies raise in Q1 2026?
Israeli tech companies raised approximately $3.1 billion across 98 funding rounds in the first quarter of 2026, a 34% increase compared with the same period the year before.
What share of Israeli VC funding comes from foreign investors?
Foreign investors accounted for about 65.9% of total Israeli tech venture capital funding in Q1 2026, according to Ecomnews Med’s reporting.
Which sector attracted the most Israeli VC funding in early 2026?
Cybersecurity attracted the largest share, accounting for roughly 40% of total Israeli tech VC funding in the first quarter of 2026.
Do Israeli VC firms only invest in Israeli companies?
No, many Israeli VC firms invest with an explicit assumption that portfolio companies will expand into international markets, most commonly the United States and Europe, from an early stage.

The AI Isn’t Wrong About Your Company. Your Sources Are | Interview with Aia Laser

Should B2B Brands Optimize for Specific AI Engines? How ChatGPT, Google, Perplexity, and Claude Compare

What Is a Blow Molded Case? Process, Materials and Trade-offs Explained

-
 Business Solutions2 years ago
Live Video Broadcasting with Bonded Transmission Technology
-
 Business Solutions2 years ago
The Future of Healthcare SMS and RCS Messaging
-
 Business Solutions2 years ago
2-Way Texting Solutions from Company Message Services
-
 Business Solutions2 years ago
Communication with Analog to Fiber Converters & RF Link Budgets
-
 DSRC Communication2 years ago
The Crossroads of Connectivity: DSRC vs. C-V2X Technologies in Automotive Communication
-
 Business Solutions2 years ago
Wholesale SMS Platforms with OTP Services
-
 Business Solutions2 years ago
Choosing the Right B2B Digital Marketing Agency: A Guide
-
 3D Technology2 years ago
How Multispectral Cameras Advance Book Scanning